RHB Research has maintained its BUY call on Samaiden Group Bhd and raised its target price to RM3.15 from RM3.00, citing the group’s growing renewable energy project pipeline and strong positioning within Malaysia’s expanding solar market.
The revised target price implies about 11% upside, alongside an estimated 1% FY2028 dividend yield.
RHB said Samaiden remains one of its preferred proxies for Malaysia’s renewable energy expansion, supported by continued policy backing, a sizeable orderbook and the prospect of another record year.
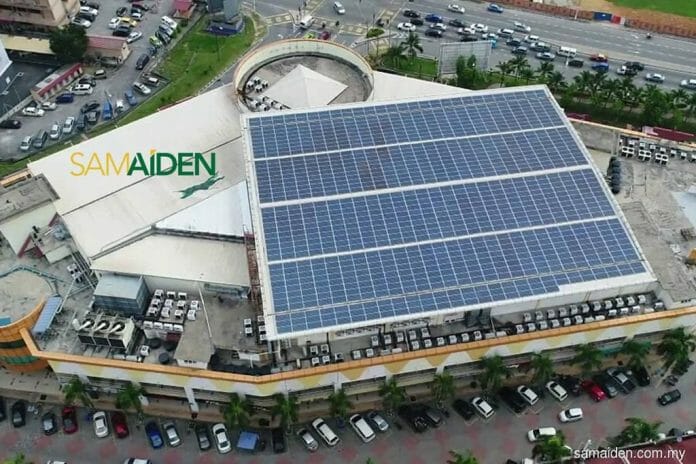
The group recently secured its first project win for FY2027 after wholly-owned Samaiden Sdn Bhd entered into contracts on Oct 2 to undertake engineering, procurement, construction and commissioning works, as well as the procurement and supply of solar components, for a 99.99MWac large-scale solar photovoltaic project under the LSS5+ programme.
While the contract value was not disclosed, RHB estimated the project could be worth around RM300 million.
The win forms part of the research house’s RM750 million FY2027 orderbook replenishment target for Samaiden.
RHB also expects the group to secure another 100MW Corporate Renewable Energy Supply Scheme project by the first quarter of 2027, in order to capitalise on the 14 sen per kWh system access charge.
The research house said the project would need to reach commercial operation by 2028, given that construction could take between 18 and 24 months.
RHB estimated Samaiden’s outstanding orderbook could rise to about RM735.8 million, from RM435.8 million as at FY2026, before accounting for revenue recognition in the first quarter of FY2027.
However, margins on the latest project are expected to normalise to around 7%, as the contract will not benefit from the exceptional margins previously generated from strategic solar panel procurement completed by end-2025.
Most of the project’s revenue is expected to be recognised in FY2028.
RHB also raised its FY2028 and FY2029 earnings forecasts by 11.4% and 14.5% respectively, after factoring in an additional RM500 million of potential job wins from the LSS6 programme.
This lifts RHB’s assumed total LSS6 job wins for Samaiden to RM2 billion, equivalent to an estimated 15% share of the available LSS6 EPCC opportunity.
The research house said this remains consistent with Samaiden’s historical 10% to 15% market share in large-scale solar projects.
Key downside risks include the withdrawal of solar incentives, increasing competition and higher-than-expected project costs.