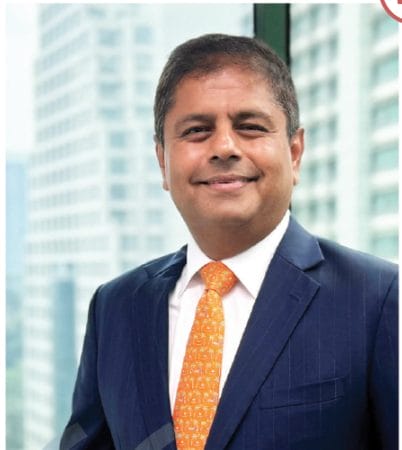
The following commentary is contributed by Bank of America country executive (Malaysia) Gautam Puntambekar
When the International Monetary Fund (IMF) and the World Bank kick off their 2026 annual meetings in Bangkok mid-October, Southeast Asia will naturally sit at the centre of the global financial conversation. The timing is apt: Shifting supply chains, geopolitical uncertainty and growing global fragmentation are forcing companies and investors to reassess where to deploy capital and where to find stability, long-term growth and reliable returns.
In this environment, Malaysia’s investment story stands out, signalling both resilience and a structural repositioning of the country globally.
The numbers reflect that. Malaysia equity capital markets volumes rose nearly 70% year-on-year to US$4.1 billion in the first nine months of the year to end-September 2026, while M&A activity saw a 58% spike to US$12.6 billion. Overall investment banking deal value rose 11% to US$40.1 billion.
This growth comes alongside a record RM426.7 billion in approved investments in 2025, with foreign and domestic investors contributing almost equally. This shows confidence in Malaysia from both global and homegrown investors, reinforcing the country’s ability to anchor long-term investment rather than rely on cyclical inflows.
Malaysia’s investment banking surge
Malaysia’s investment banking strength is particularly notable, given the global macro backdrop.
The IMF’s July 2026 World Economic Outlook projects global growth of a modest 3% this year, rising to 3.4% in 2027. Against this relatively subdued outlook, Malaysia’s deal activity suggests more than just broad-based economic expansion. It reflects a deliberate reallocation of capital as companies rethink where to base their next phase of investment, manufacturing and supply chain capacity.
Take M&A. Full-year 2025 M&A volumes reached US$19.3 billion. That momentum has continued into 2026, with inbound M&A rising meaningfully. While outbound investment has slowed, Malaysian corporates are continuing to divest offshore assets, with US$2.6 billion in such transactions this year. Together, these trends point to companies actively reshaping their portfolios to align with a more complex global environment.
Growth has been strong across other asset classes, too. Bursa Malaysia and the ACE Market have long had a steady pipeline of small listings, but this year, the country saw its largest IPO in nine years, worth US$836 million. A potential reopening of the large-cap IPO market may be on the cards, especially as the exchange prioritises scale and quality over quantity.
Debt capital markets have also been firing on all cylinders, remaining the largest contributor to overall investment banking deal value, hitting US$23.4 billion in the year to end-September. The deep, competitive and liquid ringgit market continues to differentiate Malaysia, particularly when global fundraising conditions become more volatile.
What investable looks like
Beyond capital markets, the sectors attracting capital today shed light on why Malaysia’s appeal is rising.
Digital infrastructure is one clear example. Data centres are driving much of Malaysia’s capital expenditure momentum, with Johor emerging as a main destination. Malaysia has 143 approved data centre projects, which between 2021 and June 2025 would generate cumulative investments of about RM145 billion.
Their significance go beyond the data centres themselves. Digital infrastructure is catalysing demand for power, construction, connectivity and technology, helping bolster Malaysia’s investment ecosystem. As global cloud providers and technology companies expand their regional footprints, Malaysia’s ability to offer land, power, regulatory clarity and proximity to regional hubs has become a competitive advantage.
Semiconductors are following a similar trajectory. Malaysia has long been an important assembly and packaging hub, but companies are increasingly seeking backward integration and higher-value capabilities. As supply chains diversify, Malaysia has a clear opportunity to move up the semiconductor value chain rather than simply capturing more volume.
Additionally, the electronics and electrical sectors remain Malaysia’s largest contributor to exports, reinforcing the country’s existing industrial base and its potential to benefit from supply-chain diversification.
Tying these elements together is Malaysia’s deep onshore liquidity and competitive funding costs that enable companies to finance their investments efficiently. Policy continuity and consistent engagement between industry and government agencies have further strengthened investor confidence over time — an increasingly scarce commodity as the world becomes more fragmented.
Malaysia’s next chapter
Malaysia’s appeal is clear to both domestic and international investors. The foundations are already in place: a strong investment banking environment, solid domestic liquidity, strategic infrastructure investment, a growing semiconductor and data centre ecosystem and a stable policy environment. These ensure that capital entering the country becomes embedded in its next phase of economic development.
The momentum is real and the fundamentals are strong. Malaysia is now entering a pivotal moment — one defined by its ability to attract capital, and effectively turn that global interest into sustained, long-term commitments.