South Korea’s excess tax revenue could exceed 50 trillion won (US$37 billion) this year, helped by a stronger-than-expected semiconductor cycle and improved corporate earnings, according to a Yonhap report.
The potential windfall would push the government’s available fiscal resources higher, with the Future Response Fund potentially exceeding 200 trillion won. The fund is designed to channel additional tax revenue towards strategic investment and provide reserves to support public finances.
Gains in corporate tax, income tax, value-added tax and securities transaction taxes have driven the stronger tax intake. Semiconductor companies have been a key contributor, with stronger earnings boosting corporate tax receipts.
Bloomberg reported the Yonhap estimate as the government prepares to publish a revised 2026 national tax revenue forecast later this month. The Finance Ministry said on Sunday, however, that the revised estimate has not yet been finalised.
The additional revenue could give Seoul more room to fund spending without increasing borrowing by the same amount. Under the proposed 2027 budget, part of the semiconductor-driven windfall is expected to support investment in artificial intelligence, chips, youth programmes and regional development, while also helping to reduce planned bond issuance.
The final size and allocation of the surplus will depend on the government’s updated revenue estimate, due later this month.
Hiap Teck Venture Bhd (HTVB) delivered a 24.4% increase in financial year 2026 core earnings to RM125.8 million, slightly exceeding Hong Leong Investment Bank (HLIB) Research’s expectations on stronger-than-anticipated performance from its manufacturing segment.
In a research note, HLIB said the steel group’s full-year core profit accounted for 106.1% of its earnings forecast, driven primarily by improved contributions from the trading and manufacturing divisions.
Fourth-quarter core earnings rose 60.6% quarter-on-quarter to RM39.4 million, despite revenue declining 38.3%, as higher selling prices and improved operating performance at its 27.3%-owned joint venture, Eastern Steel Sdn Bhd (ESSB), offset lower sales volumes.
On a year-on-year basis, however, fourth-quarter core profit declined 27.3%, mainly due to a weaker contribution from ESSB.
Hiap Teck has proposed a dividend of 0.7 sen per share, with the entitlement and payment dates to be announced later.
HLIB said domestic steel demand should continue to benefit from infrastructure development, manufacturing activities, industrial investment and the expansion of Malaysia’s data centre sector.
Nevertheless, the research house noted that management remained cautious about the near-term outlook amid persistent supply-demand imbalances and exports from major steel-producing countries.
HLIB maintained its earnings forecasts pending further updates from management.
The research house also reiterated its BUY rating and unchanged target price of RM0.35, based on five times average core earnings per share of 7.1 sen for FY2026 and FY2027.
At a share price of RM0.255, Hiap Teck was trading at 3.5 times forecast FY2027 earnings and 0.26 times book value, according to HLIB.
Hextar Global Bhd executive vice chairman Dato’ Ong Soon Ho’s indirect shareholding in the company has declined following the disposal of 13.89 million shares by Dato’ Ong Choo Meng for a total consideration of approximately RM10 million.
Hextar Global said Ong Choo Meng disposed of 5.55 million shares on Sept 23 for RM3.996 million, followed by another 8.34 million shares on Sept 24 for RM6.004 million.
Both transactions were carried out through direct business transactions at an implied price of 72 sen per share.
The shares were held under a pledged securities account with Phillip Nominees (Tempatan) Sdn Bhd in the name of Ong Choo Meng.
Following the disposals, Ong Soon Ho’s indirect or deemed interest in Extar Global stood at 2.15 billion shares, representing 54.886% of the company’s issued share capital.
Dato’ Ong is the father of Dato’ Ong Choo Meng and a directors and shareholder of the Company’s substantial shareholder, Hextar Holdings Sdn Bhd. Save as disclosed, he has no family relationship with any Director and/or major shareholder of the Group and has no business or other relationship which could materially pose a conflict of interest or interfere with the exercise of his judgement when acting in the capacity of a Director of Hextar which would be disadvantageous to the Group.
Engtex Group Bhd could be poised for a technical breakout towards RM0.465–RM0.515, supported by improving earnings momentum, recovering steel demand and growing opportunities in water infrastructure projects, according to Hong Leong Investment Bank (HLIB) Research.
In its latest technical and fundamental assessment, HLIB said Engtex had staged a mild rebound to close at RM0.445 after retreating from its year-to-date high of RM0.59 to a low of RM0.39.
The research house said the stock was forming a higher-low pattern after reclaiming its short-term moving averages and moving above the 23.6% Fibonacci retracement level, signalling a potential symmetrical triangle breakout.
A decisive move above RM0.465 could open the way towards RM0.49 and RM0.515, corresponding to the 50% and 61.8% Fibonacci retracement levels, respectively.
On the downside, HLIB identified support at RM0.43, followed by RM0.415 and RM0.39, with a cut-loss level at RM0.41.
HLIB said Engtex’s improving financial performance strengthened the fundamental case for the stock.
The group recorded second-quarter 2026 revenue of RM373.4 million, up 15.8% quarter-on-quarter and 8.5% year-on-year.
Net profit rose 30% quarter-on-quarter and more than 300% year-on-year to RM12.1 million, lifting first-half earnings to RM21.3 million, an increase of more than 600% from a year earlier.
The stronger results were driven by recovering steel demand and lower unit costs following higher production and delivery volumes.
HLIB expects the earnings recovery to continue into the second half of 2026, supported by cost optimisation and a more favourable product mix featuring higher-margin steel products.
The research house highlighted Engtex’s approximately RM2 billion tender pipeline, which could progressively translate into new contracts as Malaysia accelerates non-revenue water reduction programmes and upgrades its water infrastructure.
Demand for water pipes is also expected to benefit from data centre expansion, with HLIB citing 8.35 gigawatts of approved electricity supply agreements and a further 5GW in the pipeline.
The growth of data centre operations could increase demand for water capacity expansion and pipe replacement, supporting longer-term demand for Engtex’s core products.
HLIB noted that Engtex was trading at 5.9 times forecast FY2027 earnings, below its five-year mean of 39.4 times, as the group’s earnings recovery and exposure to water infrastructure investment underpin its medium- to long-term outlook.
The FBM KLCI is approaching a crucial technical support level of 1,660 points for the third time, however MBSB Research is anticipating a potential upside over the coming months despite continuing geopolitical tensions and elevated oil prices.
In its latest market outlook, the research house said the benchmark index had traded sideways between 1,660 and 1,760 points since the US-Israel-Iran conflict began in late February.
MBSB believes a sustained rebound towards the 1,760-point resistance level is possible if improving technical indicators are accompanied by easing oil prices, resilient domestic economic growth and a stable ringgit.
It said a bullish divergence, indicated by the Relative Strength Index (RSI) forming higher lows while the index tests support, alongside a positive turn in the Moving Average Convergence Divergence (MACD), could signal renewed buying interest.
MBSB identified a decline in Brent crude prices to US$80–US$85 per barrel as a potential catalyst for Malaysian equities, as lower energy costs could ease global inflationary pressure.
Brent was trading at around US$105.50 per barrel in the report.
The research house also pointed to Malaysia’s economic resilience, citing second-quarter GDP growth of 6.0% year-on-year, up from 5.4% in the first quarter, as a factor supporting investor confidence.
It added that the ringgit’s relative resilience against the US dollar could encourage foreign investors to return to Malaysian equities.
However, a decisive break below 1,660 points could expose the KLCI to further declines towards 1,640 points or the psychological 1,600-point level, MBSB cautioned.
Potential downside triggers include a fresh surge in crude oil prices, stronger global inflationary pressure and a more hawkish US Federal Reserve, which could prompt capital outflows from emerging markets.
Despite these risks, MBSB said it sees greater potential for a near-term market recovery and favours fundamentally sound stocks with double-digit expected price returns.
Its selected stocks include YTL Corporation, Gamuda, IJM Corporation, Inari Amertron, Johor Plantations and Genting Plantations.
There is something increasingly strange about legal education.
Law firms are integrating artificial intelligence into research, drafting, document review and knowledge management. Professional regulators are issuing guidance on how lawyers should use it responsibly. Courts are confronting AI-generated submissions and demanding greater human verification.
Yet some law schools still respond with a simple instruction: do not use it.
That position may feel safe. It is not. A law school cannot prohibit students from meaningfully engaging with AI while claiming to prepare them for contemporary legal practice.
This is not an argument for unrestricted AI use. It is an argument for something harder: teaching students how to exercise legal judgment when AI is available.
The professional direction is already becoming clear. The Malaysian Bar’s guidance on generative AI emphasises human oversight, verification and professional responsibility. The Solicitors Regulation Authority in England and Wales similarly warns that lawyers remain responsible for work produced with AI assistance. In the United States, courts are considering stronger requirements for human review of AI-assisted filings.
The message is not “let AI do the lawyer’s work”. It is: use the technology, but remain responsible for the law.
That is precisely why law schools must teach it.
The risks are not an argument against teaching AI. The risks are the curriculum.
Students need to learn why a convincing AI-generated case may not exist; when confidential information should never be entered into a system; how to verify authorities; how to distinguish organisation from legal reasoning; and how to recognise an answer that sounds sophisticated but is doctrinally wrong.
One does not acquire those abilities by being told never to touch the technology.
Law schools should instead create three learning environments.
First, an AI-free zone. Students must still demonstrate that they can read judgments, interpret statutes, identify legal principles and construct arguments unaided. Some foundational assessments should remain deliberately AI-free. Students cannot supervise reasoning they never learned to perform.
Second, an AI-assisted zone. Students may use AI but must disclose how. They might compare their interpretation of a case with an AI-generated interpretation, improve a draft argument and then explain which suggestions they rejected and why. The objective is no longer simply the polished final answer. It is to make judgment visible.
Third, an AI-required zone. Give students a difficult client problem and require them to use AI. Then assess the quality of their instructions, the mistakes they detect, the authorities they independently verify and the professional judgment they exercise before submitting the final work.
The sequence is simple: first, think without AI. Second, work with AI. Third, audit the AI.
This also changes assessment. For decades, legal education has largely assessed finished products: essays, memoranda, problem answers and examination scripts. Generative AI makes polished prose increasingly cheap. What becomes valuable instead is intellectual provenance.
How did the student reach the conclusion? Which authorities were checked? What did the AI suggest? What was wrong with it? What did the student change, and why?
Assessment must therefore move beyond “What is your answer?” and begin asking, “Show me your judgment.”
That is not lowering academic standards. It is raising them.
There will be discomfort. Some students will try to outsource their thinking. But prohibition can hide that problem rather than solve it. A student who secretly uses AI badly learns nothing about responsible use. A student required to expose, defend and critique that use can be taught something far more valuable.
The purpose of a law school has never been to protect students from difficult tools. It is to prepare them to exercise judgment in a difficult world.
Artificial intelligence has entered that world.
Law schools therefore face a choice: teach students to govern the technology, or send them into practice to discover its dangers by themselves.
They cannot indefinitely ban AI and still claim to produce AI-ready lawyers.
Associate Professor Dr Shahrul Mizan Ismail Faculty of Law Universiti Kebangsaan Malaysia (UKM)
Recently, under the 13th Malaysia Plan, the government floated a potential policy shift: future EPF members might receive their retirement savings as monthly payouts instead of a lump-sum withdrawal upon reaching retirement age.
The moment this news hit the airwaves, social media and WhatsApp groups erupted into a chorus of outrage.
“This is my hard-earned money! Why should the government dictate how I spend it?”
“I’ve worked my fingers to the bone for decades just so I could enjoy a big, lump-sum payout when I retire!”
As a financial educator, I completely understand that visceral emotional reaction. But financial planning isn’t governed by raw emotion. It’s anchored in cold, hard logic and structural foresight.
What Is the EPF Anyway? It’s Not a Bonus, It’s Your Financial Lifeline
Many Malaysians treat their Employees Provident Fund (EPF) savings like a retirement bonus—a pot of gold at the end of a grueling tunnel. You work hard for decades, cross the finish line at 55 or 60, and finally cash out the whole sum to buy a new car, clear loans, fund a dream vacation, or renovate the house.
The reality, however, is starkly different: Your EPF is not a reward, but your fundamental lifeline for the decades ahead.
Today, average life expectancy in Malaysia has surpassed 76 years. If you retire at 60, you are looking at two decades—or more—of retired life. Your EPF is very likely the single most reliable stream of cash flow standing between you and absolute financial destitution. It isn’t a windfall to splurge on luxury items. Lump-Sum vs. Monthly Payouts: Which System Actually Wins?
Let’s break down the pros and cons of both approaches:
Lump-Sum Withdrawal vs. Monthly Payout Comparison
Dimension
Lump-Sum Withdrawal
Monthly Payouts
Advantage 1
Ultimate flexibility for major expenses or investments.
Steady, disciplined cash flow for predictable budgeting.
Advantage 2
Psychological satisfaction of holding your entire wealth.
Built-in protection against reckless, impulsive spending.
Advantage 3
Direct autonomy over where to deploy your capital.
Strict risk mitigation against rapid capital depletion.
Disadvantage 1
High vulnerability to running through funds prematurely.
Reduced immediate autonomy over your own funds.
Disadvantage 2
High risk of scams, speculative losses, or family borrowing.
Inability to immediately clear high-interest lump-sum debts.
Disadvantage 3
Severe inflation risk if funds aren’t reinvested wisely.
Both mechanisms have distinct trade-offs. The ultimate question is simple: Do you possess the discipline and financial literacy to manage a massive pile of cash safely for 20-40 years?
Most Malaysians Are Not Ready for Retirement
According to EPF’s own data, the average 55-year-old member retires with a median savings of roughly RM240,000.
Let’s do some elementary math. If that RM240,000 has to last you 20 years, it breaks down to roughly RM1,000 a month.
Is that genuinely enough to survive on? Let’s not forget the steady creep of medical inflation, soaring food prices, and routine home maintenance. Furthermore, history shows that a segment of retirees who receive a lump sum end up sinking it into unproven businesses, speculative schemes, or luxury purchases, watching it evaporate within three years. Left with empty pockets, they become financially dependent on their children or forced to seek government assistance.Designing a Robust Retirement Portfolio: The Case of “Ah Chen”
Instead of viewing retirement as relying on a single pot of money, look at it as a diversified cash flow ecosystem. EPF is merely one component of that ecosystem, not the entire universe.
Let’s examine how a disciplined investor, let’s call him “Ah Chen,” structures his retirement wealth.
Ah Chen’s Baseline Profile:
Retirement Age: 55
Total Net Worth: RM3,000,000
RM1,000,000 sitting safely in EPF
RM1,000,000 deployed in liquid equities and growth assets
RM1,000,000 tied up in real estate (primarily rental-generating property)
Investment Capability: An experienced investor averaging a 10% annual return, translating to RM300,000 per year.
Withdrawal Strategy: He limits his first-year expenditure to RM240,000, retaining a surplus buffer to outpace inflation and allow his asset base to compound.
Pillar 1: The Essentials Fund
Ah Chen’s baseline living expenses run at roughly RM10,000 a month.
To ensure ultimate peace of mind, he carves out a 3-year living expense buffer: $10,000 x 36 =RM360,000.
He keeps this liquidity pool inside his EPF account, leveraging its stable, risk-managed dividends and flexible withdrawal mechanisms.
This ensures that during market downturns, he never has to panic-sell stocks or liquidate property at a loss to buy groceries.
Pillar 2: The Growth Fund
Ah Chen keeps RM1,000,000 actively invested in global equities.
His portfolio spans blue-chip global giants (e.g., tech and retail leaders) and high-dividend local and international counters.
The explicit goal here is capital appreciation and dividend harvesting, ensuring his wealth outlives him over a 25-to-30-year horizon.
Pillar 3: The Healthcare Buffer
Ah Chen opts for a high-deductible medical insurance policy (for instance, a RM20,000 deductible clause).
He sets aside a dedicated RM20,000 medical emergency fund, relying on EPF liquidity or cash reserves for minor medical outlays while letting comprehensive insurance shoulder catastrophic hospital bills.
This keeps his recurring premium costs low while safeguarding his primary wealth from medical drain.
Pillar 4: The Fun Fund
Retirement shouldn’t be about bare survival. Please live with vibrance.
He budgets an extra RM10,000 monthly for leisure—traveling to Hokkaido for hot springs, picking up jazz piano, or taking his grandchildren on holiday.
He recognizes that experiencing joy in retirement is about budgeted, intentional pleasure.
Dynamic Adjustments and Future-Proofing
Ah Chen applies an inflation-adjustment mechanism, recalibrating his annual spending based on macro-economic shifts and portfolio performance.
Should his EPF liquidity pool deplete, he systematically harvests dividends from his equities or rental income to maintain his 3-year cash buffer.
Through this cyclical approach, he maintains a steady artificial “salary” without feeling squeezed or financially vulnerable.
The lesson from Ah Chen’s playbook is clear: You don’t have to rely exclusively on your EPF, nor do you have to drain it in one go. What you need is a framework that keeps your money working, protects your peace of mind, and keeps your family secure.
EPF Dividends vs. Self-Directed Investing
EPF historically delivers steady, respectable annual dividends ranging between 5% and 6%. The core dilemma for many aspiring investors is: Can you consistently beat that return on your own?
If you possess the skill, discipline, and emotional fortitude to generate a steady 10% or higher net return year after year, then managing your own capital makes absolute sense.
If you don’t—and let’s be honest, the stock market is remarkably humbling—leaving your core savings within the institutional safety of EPF while drawing down only what you need is a far safer bet. The objective is to protect your financial survival, not to prove how smart you are!
Crucially, under current frameworks, this monthly payout policy does not impact existing members. You retain the freedom to choose lump-sum withdrawals, partial withdrawals, or periodic structures. The policy discussion primarily targets future generations of new members—the younger demographic who need systemic safeguards the most.
Retirement Planning is About Net Asset Health
Many people view retirement strictly through the lens of “How much cash hits my bank account each month?” This is a fundamental misconception.
True financial security relies on whether your overall asset ecosystem remains healthy and productive. Passive income buzzwords sound wonderful, but structural resilience comes down to three things:
Whether your asset allocation is diversified across multiple classes.
How fluidly your assets (real estate, equities, cash reserves) can be converted into liquidity when required.
Your capacity to manufacture an “artificial salary” by systematically harvesting returns rather than burning through principal capital.
Systems like America’s Social Security model distribute monthly stipends not to strip citizens of freedom, but to shield vulnerable individuals from financial mismanagement. Should Malaysia eventually refine its EPF distribution model, the underlying philosophy remains identical: ensuring a baseline safety net for society at large. Policies Change—Your Financial Mindset Must Change Faster
Regulations will shift, economic landscapes will evolve, and withdrawal mechanics will be debated. But no matter how policies adapt, the single most critical factor determining your retirement quality remains your own financial literacy and execution discipline.
Retirement is a transition into a brand-new chapter of life.
That chapter requires a plan, structural rhythm, and deep financial grounding. Stop looking at your EPF as a lottery ticket, and stop viewing regulatory safeguards as a restriction of freedom.
The ultimate objective is simple: To build a life where you have the capacity, the capital, and the peace of mind to live long, live well, and live securely.
So, start taking your retirement portfolio seriously today. Your future self will thank you for it.
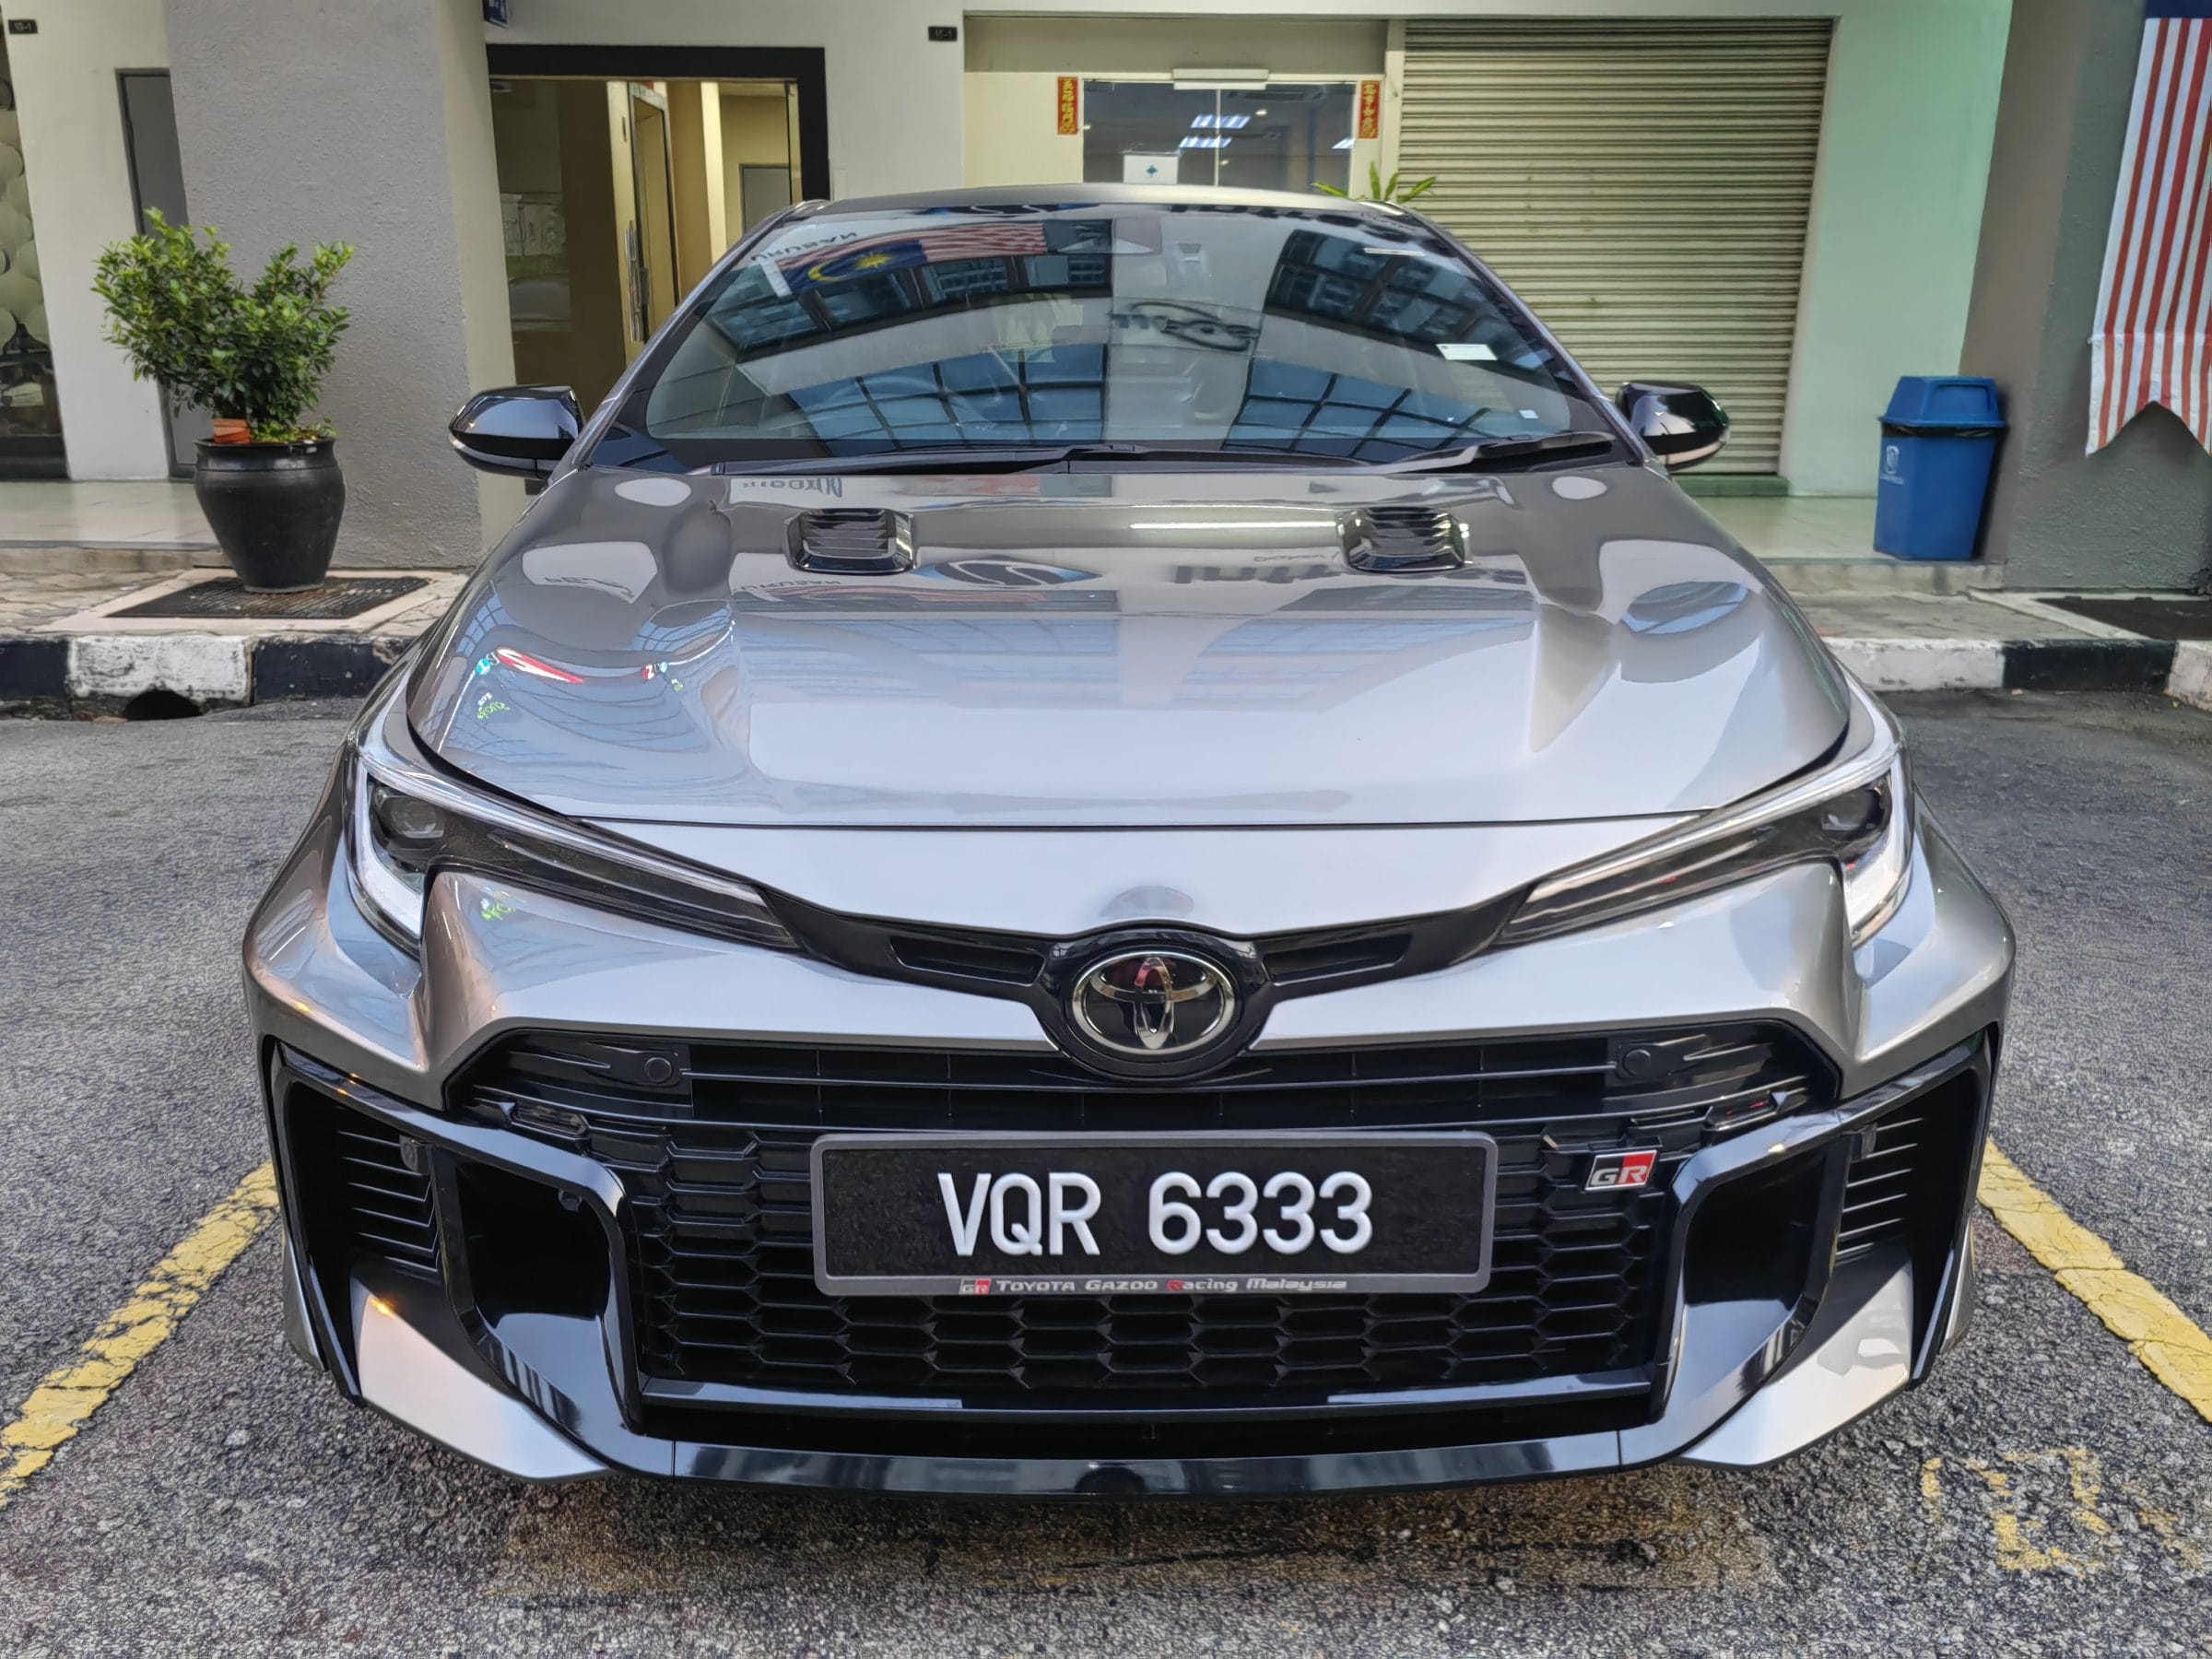
I knew the GR Corolla was going to be quick. What I did not expect was how quickly it would make me behave badly.
A squeeze of the throttle brought the turbo whistle. Brake firmly for a corner and the eight-speed automatic dropped a gear almost before I thought about doing it myself. Then the road opened up, the revs climbed and an ordinary drive became considerably less ordinary.
That happened often.
The Toyota GR Corolla AT does not need the perfect road to reveal its character because a flutter from the turbo, a changing exhaust note or an aggressive downshift is often enough to make the car feel alive.
I expected the automatic transmission to be the sensible choice. After driving it, I am not sure there is much about it that feels sensible.
Fun Comes Easily
The first thing I noticed was how little effort it took to enjoy the car.
I could start it, select Drive and get on with the journey. Even at ordinary speeds, the GR Corolla kept reminding me what was underneath.
Squeeze the throttle and the turbo starts to whistle. Push harder and the 1.6-litre turbocharged three-cylinder wakes up. Brake firmly approaching a corner and the gearbox often drops a ratio, raising the revs before I get back onto the accelerator.
That is where the eight-speed GR Direct Automatic Transmission, or GR-DAT, makes its case.
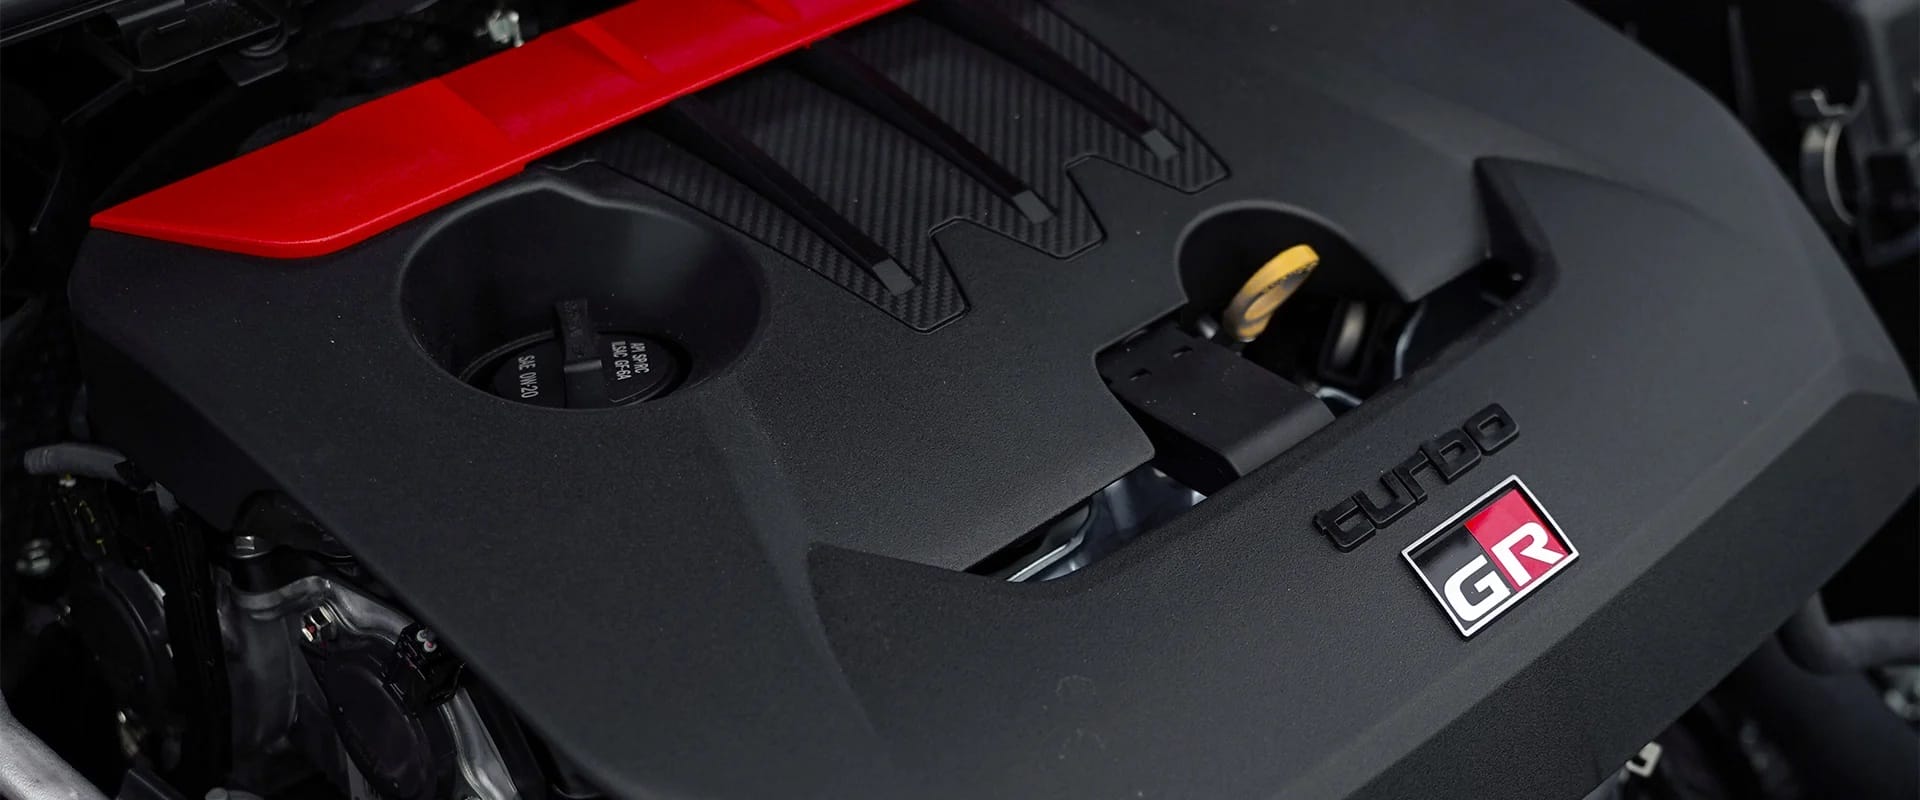
Under the bonnet of the Corolla GR is a 1,618cc G16E-GTS turbocharged three-cylinder that produces 296hp and 400Nm of torque
It is a torque-converter automatic rather than a dual-clutch unit, with shift logic developed through Toyota’s Super Taikyu endurance racing programme. The gearbox reads brake and throttle inputs to anticipate what gear I may need next.
When it works properly, I barely think about it. I can concentrate on the steering, grip and road instead.
Three Cylinders, Plenty Of Attitude
Under the bonnet is a 1,618cc G16E-GTS turbocharged three-cylinder producing 296hp and 400Nm of torque.
There is a slight pause before the turbo fully wakes up, but I actually enjoyed it.
Put my foot down and I could feel the boost building before the car surged forward. It gives the acceleration some mechanical character rather than delivering everything instantly.
Once on boost, 296 hp feels like plenty. It is quick enough to be exciting without requiring absurd speeds to enjoy it.
The soundtrack helps.
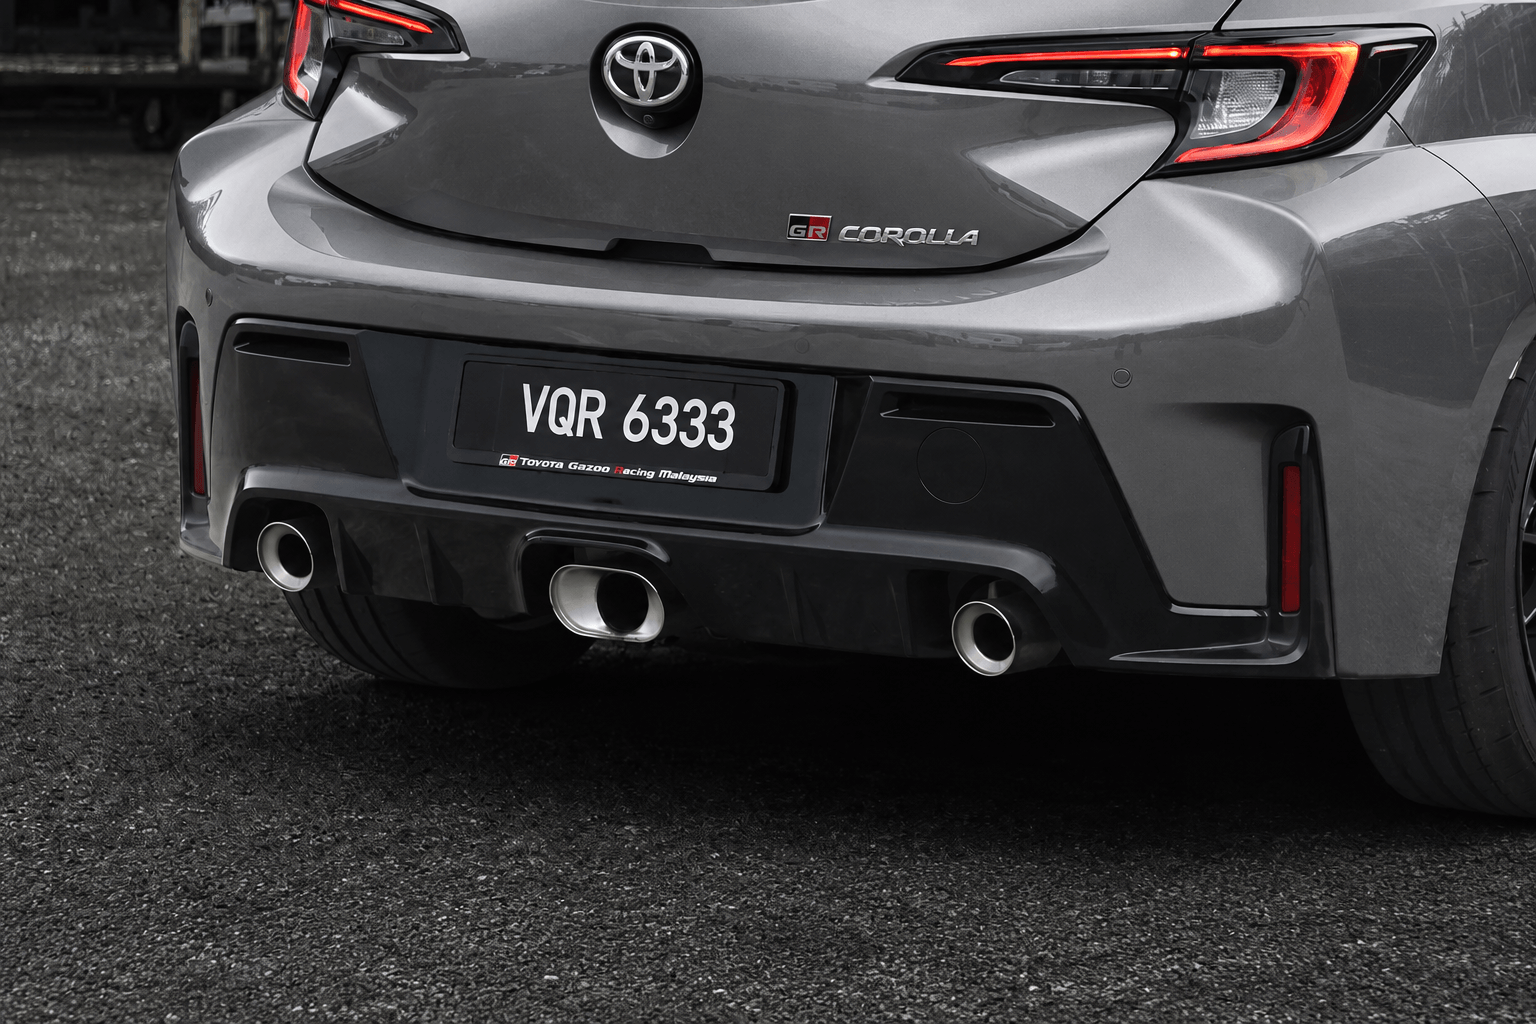
The triple exhaust configuration supports a higher output and generates a satisfyingly powerful exhaust sound
The three-cylinder has its own busy rhythm, joined by turbo whistle, occasional flutter and the changing tone of the triple-outlet exhaust. A downshift lifts the engine higher into the rev range and changes the whole sound of the car.
It is not excessively loud or theatrical. There is simply enough happening to keep me interested.
Grip I Could Feel
The GR Corolla is not delicate. It feels physical.
Turn into a corner and I could feel the tyres loading up. Get back onto the throttle and the GR-Four all-wheel-drive (AWD) system, working with front and rear Torsen limited-slip differentials, gives a strong sense of the car digging into the road and pulling itself forward.
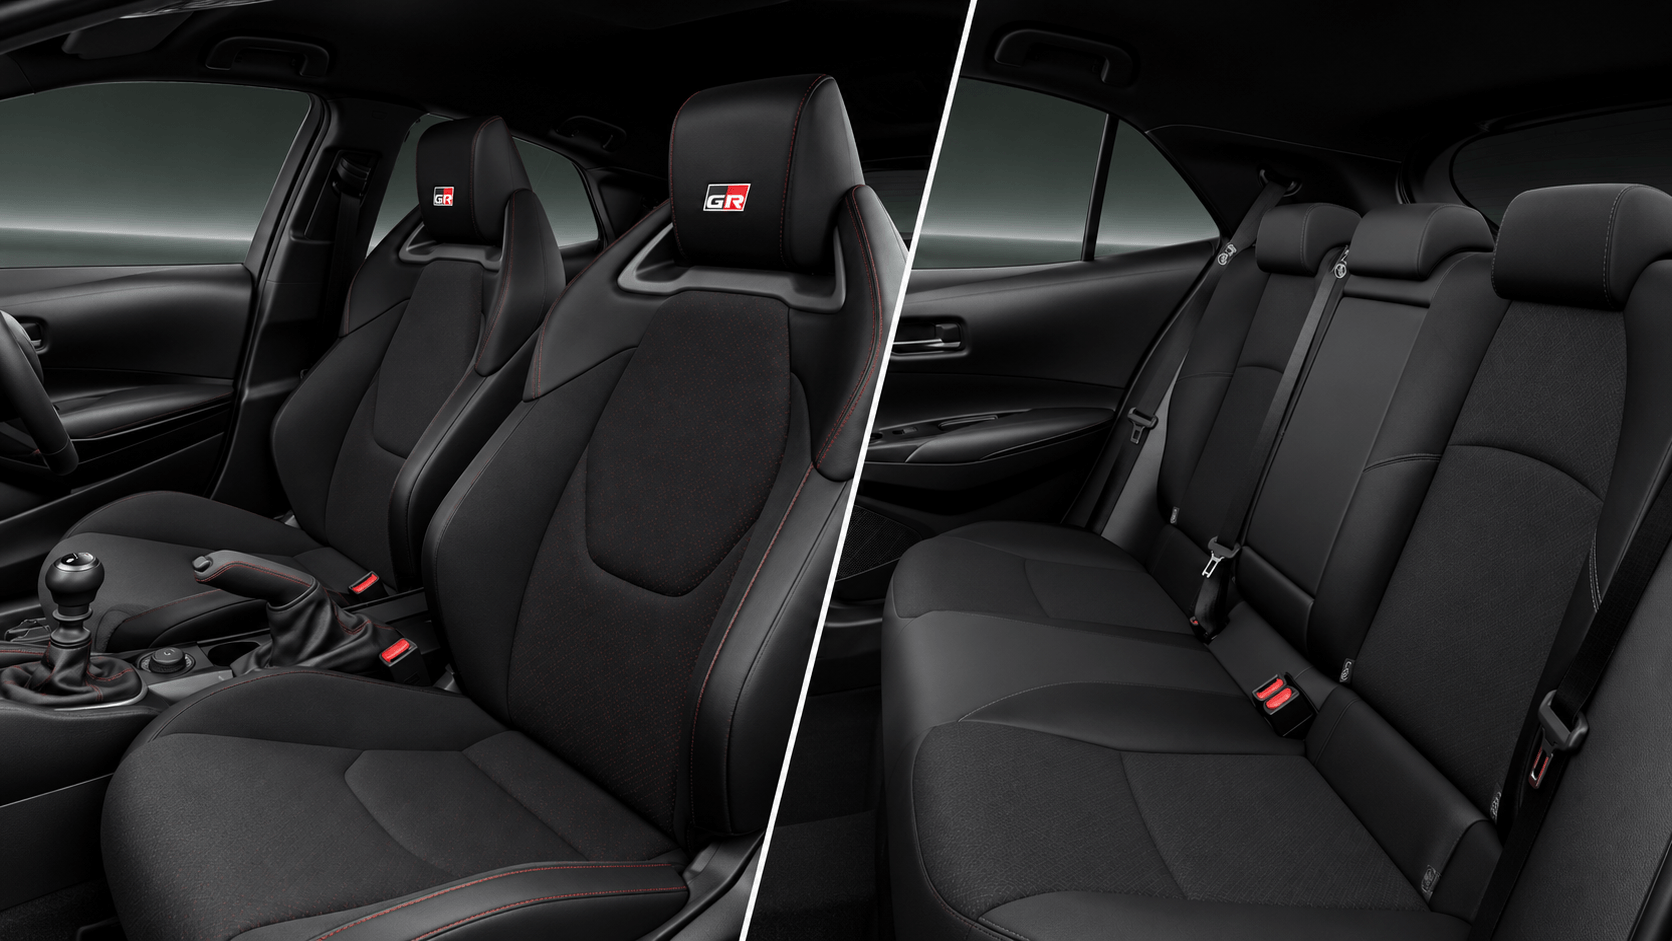
Leather and Ultrasuede seats with red accents deliver sporty comfort, with seating for five to keep longer journeys enjoyable
That mechanical connection is one of the car’s strengths. I remained aware that serious hardware was working underneath me rather than everything being filtered away.
The downside is ride quality.
The GR Corolla is stiff. Expansion joints, rough tarmac and badly repaired roads all make themselves known.
I would not call it brutally uncomfortable, but I never forgot that I was driving a performance hatchback.
Still Easy To Live With
Despite that firmness, I found the GR Corolla surprisingly usable.
The automatic made traffic easy, visibility was decent and the supportive seats never turned an ordinary commute into a chore.
The Corolla GR is your daily car best suited for work and errands without having to do any reorganising around it
It is still a five-door hatchback, which means I could use it for work, errands and everyday driving without reorganising my life around it.
Then the road cleared and the character changed almost immediately.
That contrast is what I want from a hot hatch: Practical enough for the boring parts of the week, entertaining enough to make me consider taking the longer route home.
The GR Corolla manages both.
Then there is the price.
The GR Corolla costs RM378,950 on the road without insurance, RM10,000 more than the six-speed manual.
Spend time inside and I could still find ordinary Corolla materials and switchgear. Some parts of the cabin do not immediately feel like they belong in something approaching RM380,000.
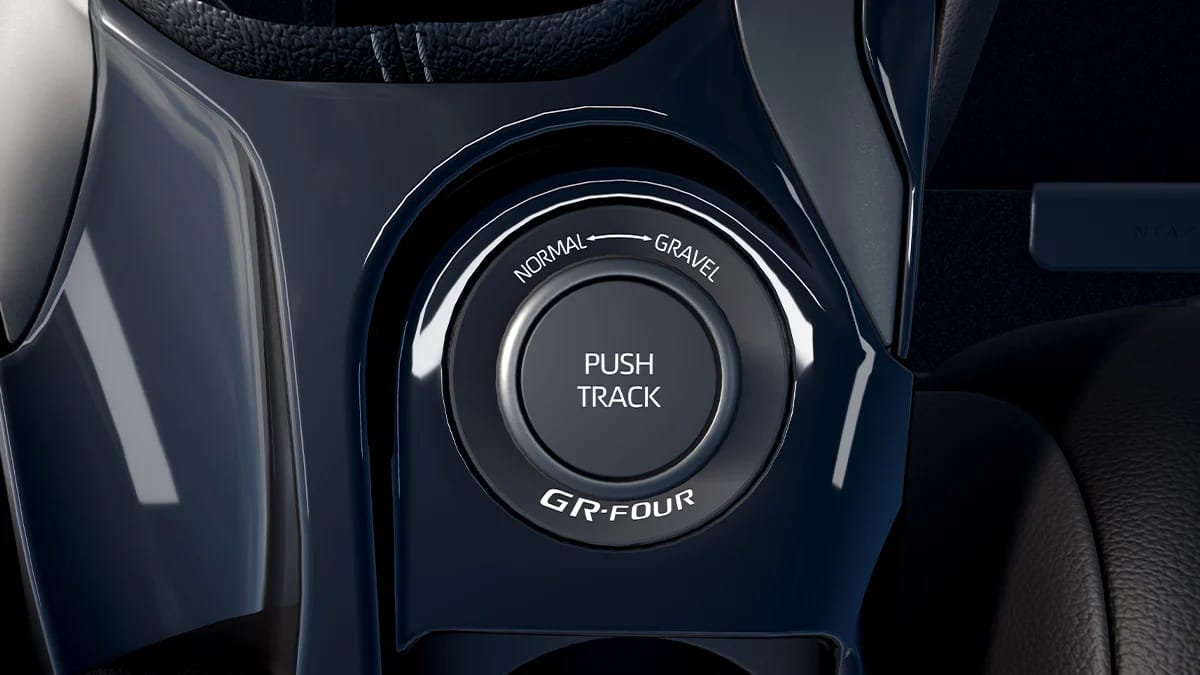
The car offers three drive modes built for different conditions — NORMAL balances at 60:40, GRAVEL locks to 50:50, while TRACK dynamically shifts between 60:40 and 30:70 for sharper traction and response
But most of the expensive engineering is underneath.
There is the turbocharged engine, GR-Four AWD, front and rear Torsen differentials, reinforced structure, suspension, cooling hardware and the eight-speed transmission. Toyota also builds the GR Corolla at its GR Factory in Motomachi with additional structural reinforcement, welds and adhesive.
That does not make it cheap. It simply means much of what I am paying for cannot be judged by looking around the cabin.
The Automatic Is Not The Compromise
After spending time with the GR Corolla AT, I stopped thinking of the automatic as the softer option.
It makes the car easier to enjoy.
I could leave it in Drive and let the gearbox do the work, yet it still kept the engine involved when the road became interesting. I did not feel as though convenience had stripped away the character.
There are compromises.
The ride is firm. Parts of the cabin are difficult to reconcile with the price. And refinement is clearly not the GR Corolla’s strongest suit.
But I also found it fast, usable and full of mechanical personality.
Most importantly, it never felt like a car I had to work hard to enjoy.
Sometimes the gearbox dropped a gear, the turbo started to whistle and the road ahead opened up.
In those moments, I simply wanted to keep driving.
Pakatan Harapan (PH) Melaka has completed seat allocations among its state-level component parties for the upcoming Melaka State Election, although the final arrangement still requires approval from the coalition’s leadership.
Melaka PH chairman Adly Zahari said the allocation would be finalised after discussions involving the PH Presidential Council, state PH and PH election director Datuk Seri Amirudin Shari.
“In any case, we will wait until next week. The election director (Amirudin) is already aware of the decision. We will take it to the coalition’s highest level for finalisation,” he told reporters after PH’s Ceramah Perdana in Bukit Baru last night.
Adly said the seat allocation within PH remained as agreed at the state level, including eight seats allocated to Parti Amanah Negara (Amanah).
He added that PH Melaka’s election strategy would be announced once the seat allocation received final approval.
Also present at the event were Amanah president Datuk Seri Mohamad Sabu and Melaka PKR State Leadership Council acting chairman Adam Adli Abdul Halim.
Standard Chartered expects the US Federal Reserve to raise interest rates twice more by mid-2027 as accelerating artificial intelligence (AI) investment and persistent inflation increase the possibility of stronger-than-anticipated economic growth.
In its latest market outlook, the bank said the likelihood of the US economy shifting from its base-case soft-landing scenario to a “no-landing” scenario had increased, supported by sustained AI-related investment.
It also expects the Bank of Japan to raise rates three more times and the European Central Bank to deliver one additional increase.
Despite the prospect of higher interest rates and bond yields, Standard Chartered remains positive on global equities, citing robust corporate earnings and economic growth.
The bank argued that the current environment more closely resembles the interest rate increases of the 1990s, when equities continued to advance alongside strong growth, rather than the inflation-driven tightening cycle of 2022.
Equity Pullbacks Seen As Buying Opportunities
Standard Chartered maintained its overweight position in equities relative to bonds and cash, although it cautioned against excessive equity exposure.
The bank favours US and Asia ex-Japan equities, where earnings expectations remain strong.
Within Asia, it has reduced its allocation to Chinese equities to a core holding, leaving Taiwan as its only regional overweight position, reflecting its preference for markets benefiting from AI investment.
It expects market volatility to persist around the US midterm elections but views further equity pullbacks as potential opportunities to increase exposure.
Corporate And Emerging Market Bonds Preferred
In fixed income, Standard Chartered favours corporate and emerging market bonds over government securities, citing strong underlying credit quality and the prospect of continued volatility in longer-maturity bonds.
It recommended maintaining bond durations of three to seven years to limit exposure to rising term premiums associated with inflation and government debt concerns.
The bank remains overweight emerging market US dollar bonds, while treating investment-grade and high-yield corporate bonds as core holdings.
Modest US Dollar Weakness, Further Gold Gains Expected
Standard Chartered expects the US dollar to resume a modest weakening trend, arguing that markets may have priced in excessive Fed tightening.
It sees scope for further interest rate increases outside the US, particularly in Japan, which could support the yen.
The bank also expects gold to rise over the next three and 12 months, supported by a softer dollar and continued demand from emerging market central banks.
However, it cautioned that gold’s advance is unlikely to be uninterrupted, with periodic corrections expected along the way.
Naval and air units of the Chinese People’s Liberation Army (PLA) Southern Theater Command conducted a joint training exercise in the waters and airspace around China’s Huangyan Dao in the South China Sea on Sunday.
A statement from the command said the exercise is a necessary operation taken in response to the acts taken by certain countries that have undermined regional peace and stability.
The training exercise aims to test and enhance the combat capabilities to safeguard China’s territorial sovereignty and maritime rights and interests, the statement said.
China has sovereignty over Nanhai Zhudao (the South China Sea Islands), consisting of Dongsha Qundao (the Dongsha Islands), Xisha Qundao (the Xisha Islands), Zhongsha Qundao (the Zhongsha Islands) and Nansha Qundao (the Nansha Islands). China has historic rights in the South China Sea.
China also has internal waters, territorial sea, contiguous zone, exclusive economic zone and continental shelf, based on Nanhai Zhudao.
Nanhai Zhudao have long been widely recognized by the international community as part of China’s territory.
Families of 55 Malaysians who remain missing following the glacial flash flood in Nepal arrived at Wisma Putra this morning for a briefing on the latest search efforts and the status of their loved ones.
The closed-door meeting, which began after 9am, is expected to provide updates on search operations and the verification and identification of victims more than a month after the Aug 26 incident.
Representatives from the National Disaster Management Agency (NADMA), Special Malaysia Disaster Assistance and Rescue Team (SMART), Royal Malaysia Police (PDRM), Department of Chemistry Malaysia, National Registration Department (JPN) and Social Welfare Department (JKM) are expected to attend the session.
The meeting is the second official engagement between the government and the affected families, following the initial briefing at Wisma Putra on Aug 30, when DNA samples were also collected to assist in identifying bodies recovered in Nepal.
A SMART team comprising 11 personnel was deployed to Nepal on Sept 5 to conduct ground searches and drone surveillance in areas approved and deemed safe by Nepalese authorities. The team returned to Malaysia on Sept 14.
Wisma Putra previously said the team’s return did not mean efforts to determine the status of the 55 Malaysians had ended, as Nepalese authorities continued search, verification and identification operations while Malaysia pursued diplomatic efforts with the relevant authorities.
On Sept 22, Prime Minister Datuk Seri Anwar Ibrahim conveyed the concerns and hopes of the families to Nepalese Prime Minister Balendra Shah and raised the need for a formal mechanism to assist them should the Malaysians remain unaccounted for.
The Aug 26 floods and debris flows, triggered by an ice and rock collapse in the upper Lhende Khola catchment area in Tibet, reportedly claimed more than 1,450 lives, while thousands remain missing.
Several Malaysians have been affected by extensive flooding across Bangkok, Thailand, prompting the Malaysian Embassy to provide assistance to those impacted, according to the Ministry of Foreign Affairs.
In a statement, Wisma Putra said the floods had affected multiple districts and major transportation routes in the Thai capital.
The ministry said the Malaysian Embassy in Bangkok had confirmed that several Malaysian nationals were among those affected and was providing the necessary support while maintaining close communication with local authorities.
“The Ministry of Foreign Affairs is closely monitoring the situation following extensive flooding across Bangkok,” it said, extending its sympathies to those affected by the disaster.
Malaysians residing in or visiting Bangkok have been advised to exercise caution, remain vigilant and comply with all safety instructions issued by Thai authorities.
Travellers heading to Suvarnabhumi Airport were also urged to allow additional journey time and arrive well ahead of their scheduled departures, as flooding could cause delays along airport access routes.
Wisma Putra strongly encouraged all Malaysian nationals in Bangkok who have not registered their presence to do so immediately through the e-Konsular system, which enables the ministry to maintain contact with Malaysians abroad and coordinate assistance when necessary.
Malaysia has called for the abolition of the United Nations Security Council veto and a greater voice for developing nations in artificial intelligence (AI) governance, warning that the international system risks losing public trust unless it delivers meaningful reforms.
Foreign Minister Datuk Seri Mohamad Hasan, delivering Malaysia’s national statement at the 81st UN General Assembly in New York on Saturday (Sept 26), said global conflicts and growing major-power rivalry had exposed shortcomings in the multilateral system.
He identified Gaza as an urgent example of the need for reform, reiterating Malaysia’s calls for an immediate ceasefire, unrestricted humanitarian aid and full Palestinian membership of the UN.
Mohamad argued that expanding Security Council membership alone would be insufficient, saying the veto itself must be abolished to improve accountability.
On AI, he said countries in the Global South must help shape international rules rather than serve solely as markets or destinations for data centres and investment.
“The Global South cannot simply become a destination for data centres, while decisions about A.I. are made elsewhere,” he said.
He also urged governments to manage the demands that technology infrastructure places on water, energy and land.
Addressing escalating conflict in West Asia, Mohamad warned that disruptions to the Strait of Hormuz and Bab el-Mandab could raise food, fuel and living costs for households far beyond the region.
He called for renewed diplomacy and said middle powers such as Malaysia, alongside regional organisations including ASEAN, could help sustain dialogue amid major-power disagreements.
Ministers can change. Rail projects, maintenance schedules and road-safety enforcement cannot afford to stop.
That, according to Monash University Malaysia senior lecturer Dr Andrew Woon, should define the Transport Ministry’s (MOT) next chapter as Anthony Loke remains firm on his decision to step down from the Cabinet.
We do have to caveat this article as the date of publishing, while Loke announced his intention to resign on Sept 19, Prime Minister Datuk Seri Anwar Ibrahim said on Sept 26 that he had yet to receive the formal resignation letter despite the Transport Minister affirmed his decision to leave the cabinet.
Speaking exclusively to BusinessToday, Woon said the immediate priority for MOT should be continuity rather than a wholesale change of direction, particularly with several major transport projects already carrying substantial long-term commitments.
Among them are the Johor Bahru-Singapore Rapid Transit System, the East Coast Rail Link and planned rail connectivity in Johor.
Any significant change in direction under a new minister, Woon cautioned, could introduce delays, uncertainty and additional costs.
Reliability Cannot Lose Momentum
Beyond headline infrastructure, Woon said the next minister should preserve the momentum made in public-transport reliability.
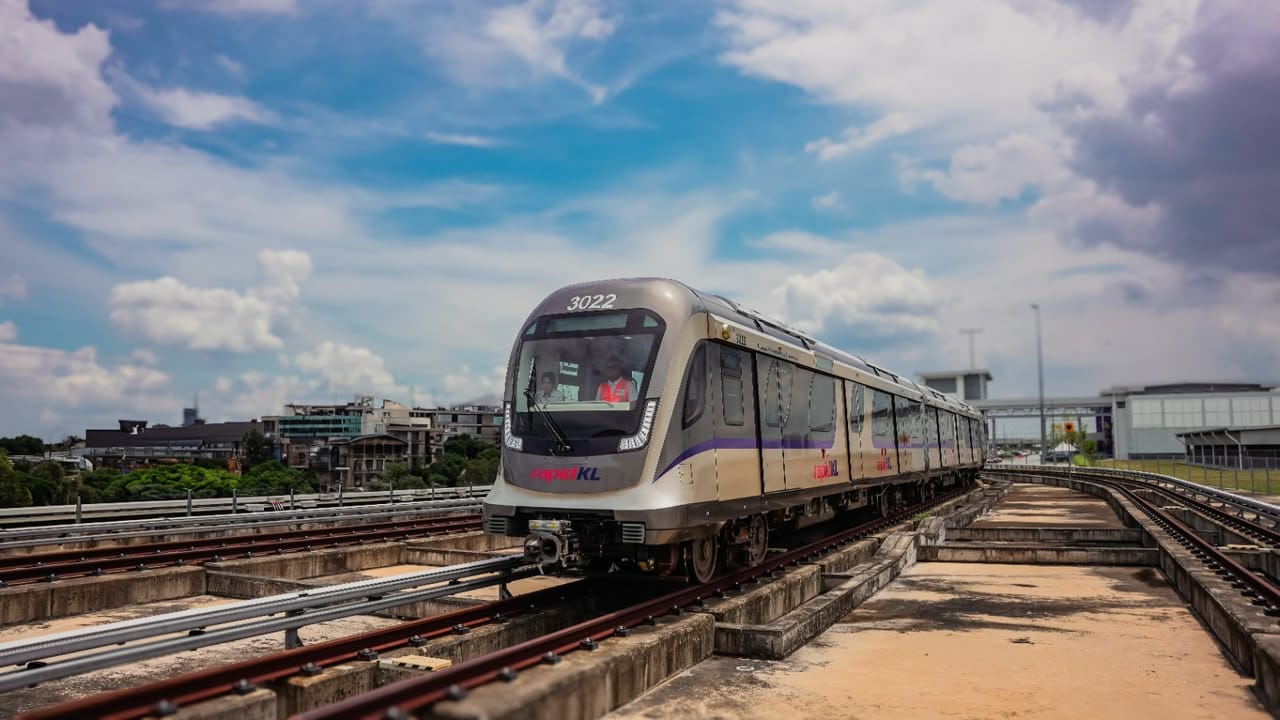
Reported LRT and MRT failures, excluding the monorail, fell from 177 in 2022 to 28 in 2025 and 12 in the first five months of 2026
Reported LRT and MRT failures, excluding the monorail, fell from 177 in 2022 to 28 in 2025 and 12 in the first five months of 2026, which he cited as one of the more measurable improvements during Loke’s tenure.
Rather than using a leadership change to reset MOT’s agenda, Woon said the successor should continue prioritising maintenance, reliability and operational performance.
The bigger test, however, may lie outside rail.
Woon warned that road-safety enforcement could be more vulnerable to a change in political leadership, as sustained enforcement often requires continued ministerial backing.
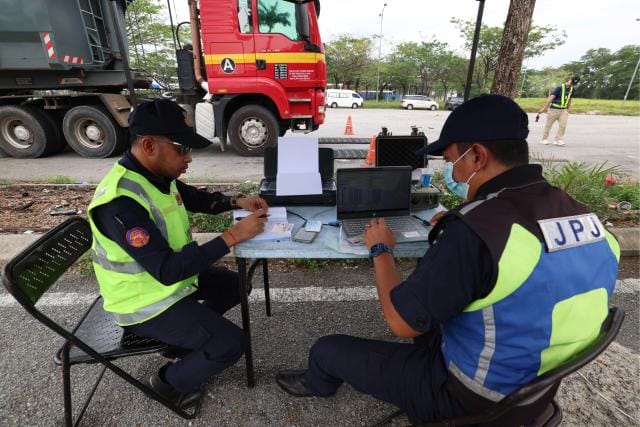
Cracking down on overloading heavy vehicles must continue despite the change in leadership
He pointed to MOT’s crackdown on overloaded heavy vehicles, under which more than 169,000 heavy vehicles were inspected in 2025 and over 3,500 found to be overloaded. Malaysia nevertheless recorded 6,537 road deaths in 2025, with motorcyclists and pillion riders accounting for about 66% of fatalities.
“The key distinction is between major projects already embedded within government institutions and enforcement programmes that still depend heavily on sustained political attention,” Woon said.
Who Should Take Over?
On who should replace Loke, Woon stopped short of naming a particular politician, arguing that the more important question is what kind of minister MOT now requires.
In his assessment, a successor should have three qualities: The ability to maintain continuity on major infrastructure projects, enough political authority to sustain difficult enforcement policies and an understanding of transport as a long-term economic and public-service issue rather than merely another political portfolio.
Even if MOT were transferred to another coalition partner, Woon said that would not automatically mean a shift in policy.
The real test would be whether the incoming minister preserves commitments on rail infrastructure, public-transport reliability, digitalisation and enforcement, with implementation capacity taking precedence over party affiliation.
Loke’s Report Card: Delivery, Digitalisation — But Road Safety Lags
Assessing Loke’s time at MOT, Woon highlighted digitalisation, improving rail reliability, the opening of LRT3 and tougher action against overloaded lorries among the more significant developments.
The expansion of the MyJPJ ecosystem moved services including driving licences and road-tax access away from physical counters, while the sharp fall in reported LRT and MRT failures pointed to improved operational reliability.
Woon, nevertheless, stressed that those improvements should also be credited to Rapid Rail, Prasarana and the technical teams involved.
He also highlighted the opening of the 37.8km LRT3 Shah Alam Line, connecting Bandar Utama and Johan Setia, alongside the ministry’s continued enforcement against lorry overloading and proposed measures to hold consignors and consignees accountable.
The analyst sees Loke as a results-oriented minister with a clear vision for improving Malaysia’s transport system
Woon characterised Loke as a results-oriented minister with a clear vision for improving Malaysia’s transport system, particularly through policies focused on public-transport reliability, digitalisation and road safety rather than solely high-profile infrastructure.
But the record remains unfinished.
For Woon, road safety is the biggest unresolved issue. Despite progress in rail services and digitalisation, the 6,537 deaths recorded on Malaysian roads in 2025 show that improvements within MOT’s administrative and public-transport functions have yet to translate into a comparable improvement in overall road-safety outcomes.
That leaves MOT’s next leadership with a relatively clear challenge: Not to reinvent the ministry, but to make sure the gains already made survive the minister who drove them.
As Woon put it, the longer-term task is to institutionalise these initiatives so they continue beyond the tenure of any individual minister.
Saudi Foreign Minister Prince Faisal bin Farhan Al Saud on Saturday stressed the importance of restoring the situation in the Strait of Hormuz to its pre-Feb. 28 status without the imposition of any fees or restrictions.
Speaking during the general debate of the 81st Session of the United Nations General Assembly, Faisal called for freedom of navigation in international waterways, highlighting the Strait of Hormuz, Bab el-Mandeb Strait, Red Sea and Gulf of Aden, and rejected their use by any party as an instrument of pressure or threat.
He said the security of the Gulf region is part and parcel of the security of the region and the world at large, adding that stability in the Gulf is directly connected to global energy security, international trade and supply chains.
He noted that Saudi Arabia supports efforts and initiatives aimed at de-escalating tensions in the region and stressed the importance of ensuring that the entire region remains free of weapons of mass destruction.
The United States and Israel launched a massive military strike against Iran on Feb. 28, after which Iran retaliated by targeting Israel and multiple sites across the Middle East. The conflict has disrupted shipping through the Strait of Hormuz, significantly affecting Saudi Arabia’s oil exports to global markets.
Floodwaters receded across parts of Bangkok on Sunday (Sep 27) after a break in torrential rain that caused severe flooding a day earlier and prompted authorities to declare the Thai capital a disaster zone.
The Bangkok Metropolitan Administration (BMA) said late on Saturday that rain had eased, with only scattered clouds remaining, allowing authorities to accelerate efforts to drain canals and lower water levels. Officials expected flooding to gradually subside if no further rain fell.
Bangkok received nearly 300mm of rainfall over 48 hours through Saturday, flooding major roads and leaving some cars partly submerged. The BMA said it had prepared 233 temporary shelters and moved around 4,200 people to shelters.
Hong Kong stocks ended the week lower, with the Hang Seng Index (HSI) falling 240.69 points or 0.97% to 24,510.09 for the week ended Sept 25, extending its decline for a third consecutive week as technology stocks came under pressure ahead of the Trump-Xi summit.
The market was closed on Monday, when the Hong Kong Exchanges and Clearing (HKEX) released proposals to ease listing rules for major transactions and spin-offs. The changes are aimed at giving listed companies greater flexibility and improving Hong Kong’s competitiveness as a listing venue.
The HSI edged 0.34% higher on Tuesday to 24,834.12, with turnover reaching HK$249.2 billion as investors tracked gains in Shanghai and selectively bought property and other mainland-linked counters.
Sentiment weakened sharply on Wednesday, however, with the index falling 1.01% or 254 points. Technology stocks led the decline as investors took profits and remained cautious ahead of the meeting between US President Donald Trump and Chinese President Xi Jinping.
Alibaba fell 4.2%, while Tencent declined 2.4% and Xiaomi dropped 3.8%. MiniMax fell 4%, while Z.AI Co plunged 12.4%.
The HSI slipped another 0.29% on Thursday to 24,761.13 as investors remained defensive ahead of the US-China talks. Finance, technology services and retail stocks continued to face selling pressure, while selected defensive and mainland-linked counters provided some support.
The decline accelerated on Friday, with the HSI falling 1.01% or 251.04 points to 24,510.09, its lowest close of the week. The Hang Seng China Enterprises Index and Hang Seng Tech Index also declined as investors reduced exposure to riskier assets ahead of the summit.
The week’s losses were concentrated in the technology sector, with concerns over AI-related stocks and profit-taking adding to broader uncertainty surrounding US-China relations.
Meanwhile, the HKEX listing-rule proposals provided a longer-term development for the market. The consultation, which runs until Nov 30, would include raising the shareholder approval threshold for major transactions from 25% to 50%, among other measures.
The HSI remains up about 1.5% year to date on a total-return basis despite the latest weekly decline.
Singapore stocks ended higher for the week ended Sept 25, with the Straits Times Index (STI) gaining 35.89 points or 0.63% to 5,711.12, recovering from a 0.70% decline in the previous week.
The index began the week with a 0.34% gain on Monday to 5,675.23, led by broad-based buying. DFI Retail Group was the top STI gainer, rising 3.21%, while Yangzijiang Shipbuilding and OCBC Bank also advanced.
The rally gathered pace on Tuesday, with the STI jumping 0.86% to 5,723.76 in its strongest single-day advance since early September. Seatrium led the gains, surging 4.9% to S$2.15, while ST Engineering and SGX Ltd each rose 2.9%. Eighteen of the 30 STI constituents gained, including all three local banks.
The market then gave back some of the gains on Wednesday, with the STI falling 0.24% to 5,709.91 as OCBC and Seatrium came under pressure. City Developments bucked the broader weakness, climbing 3.7% to S$8.42, while Seatrium fell 2.3% to S$2.10.
Selling pressure intensified on Thursday, with the index dropping another 0.46% to 5,683.37 as investors turned cautious ahead of the meeting between US President Donald Trump and Chinese President Xi Jinping in Washington.
First Resources was the standout performer, rising 5% to S$4.66, but losers outnumbered gainers 300 to 231, with about 1.1 billion shares changing hands.
The STI rebounded on Friday, rising 0.49% to 5,711.12 as the three local banks advanced and helped offset concerns over elevated global bond yields and oil prices.
The weekly gain leaves the STI up 21.99% year to date on a total-return basis, despite the pullback seen in the middle of the week.
The market remained sensitive to global interest rates, oil prices and developments in US-China relations, while selective strength in banks, marine engineering and property counters provided support.
Bitcoin and Ethereum ended the Sept 21-Sept 25 week higher despite surrendering part of Sept 21’s sharp gains, as rising US Treasury yields and renewed interest-rate concerns tempered an early surge in risk appetite.
Bitcoin closed at US$84,071 on Sept 25, about 4% above its Sept 18 close of US$80,857. The cryptocurrency surged 6.68% on Sept 21 to US$86,617, reaching an eight-month high as falling oil prices, softer Treasury yields and strength in technology stocks boosted demand for risk assets.
Momentum faded thereafter as Bitcoin slipped 0.49% on Sept 22 and another 2.15% the following day to US$84,340 as bond yields climbed. It was virtually flat on Sept 24 before easing 0.34% on Sept 25. Expectations for further US Federal Reserve rate hikes weighed on cryptocurrencies during the latter half of the week.
Ethereum followed a similar pattern, finishing Sept 25 at about US$2,693, up roughly 3.1% from US$2,612 on Sept 18. Ether jumped 4.94% on Sept 21 to US$2,776 before declining over the next two sessions, including a 2.5% fall on Sept 23. It steadied on Sept 24 and edged higher the following day.
The week highlighted cryptocurrencies’ continued sensitivity to broader risk sentiment, with early support from improving liquidity conditions and regulatory optimism giving way to caution as US bond yields rose and investors reassessed the outlook for interest rates.