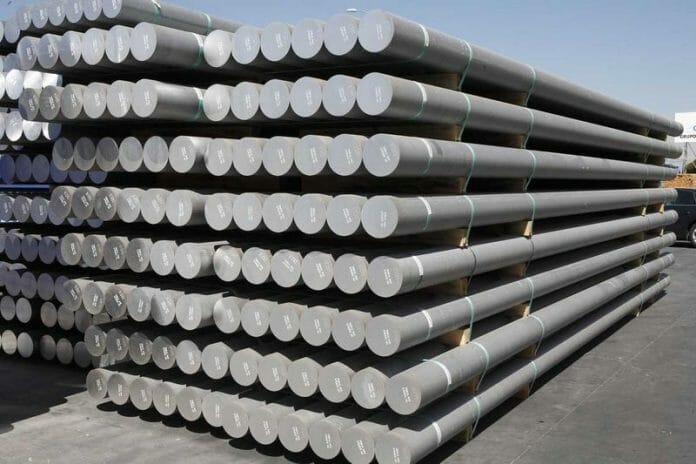
OCBC has raised its end-2026 aluminium price forecast to about US$3,150 per tonne from US$3,050, citing a slower-than-expected recovery in Gulf production, although it still expects prices to moderate from current levels as strong Chinese output offsets supply disruptions.
Three-month aluminium on the London Metal Exchange (LME) fell 0.9% month-to-date in September to US$3,214 per tonne as at Sept 29, remaining 2% above OCBC’s third-quarter forecast of US$3,150.
The cash-to-three-month spread was broadly unchanged at a US$7.40-per-tonne contango, compared with US$7.60 at end-August, suggesting limited urgency for immediate metal supply despite a continued decline in global exchange inventories.
OCBC said the recovery in aluminium production across the Gulf Cooperation Council (GCC) appears to have lost momentum. Output growth slowed to 2% month-on-month in August from 6.2% in July, amid continuing disruptions linked to the Middle East conflict.
The slower recovery suggested earlier expectations for a rapid production restart may have been too optimistic.
China, however, continues to compensate for the Gulf shortfall, with aluminium production running close to record levels. Chinese output rose 4.7% year-on-year in August, accelerating from 3.1% in July.
Exports of unwrought aluminium and aluminium products also remained strong, increasing 17.3% year-on-year, compared with 18.7% in July.
OCBC said robust Chinese production should continue to offset reduced Gulf supply as operations in the region are progressively restored.
Emirates Global Aluminium (EGA) reported in late August that 25% of the reduction cells at its Al Taweelah facility had been restored, with full production targeted by the first quarter of 2027.
Despite raising its forecast curve, OCBC said its broader view remains unchanged, with aluminium prices expected to gradually ease towards US$3,150 per tonne by end-4Q26.
The bank sees no strong catalyst for prices in either direction through the first quarter of 2027.
A further deterioration in Gulf production or a slower restart without additional Chinese supply represents the key upside risk, while a faster-than-expected Gulf recovery or weaker global demand could accelerate the anticipated price moderation.