


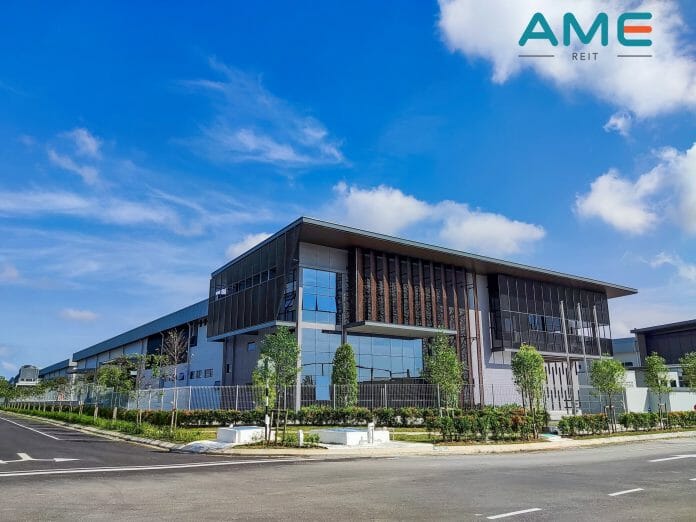
AME Real Estate Investment Trust (AME REIT) delivered a steady start to its financial year, with first-quarter earnings supported by contributions from newly acquired properties, while its latest industrial land acquisition in Johor is expected to strengthen long-term growth, according to Kenanga Research.
AME REIT posted a net profit of RM10.2 million for the first quarter ended June 30, 2026 (1QFY27), representing 24% of Kenanga’s full-year forecast and 23% of consensus estimates. The REIT also declared a gross distribution per unit (DPU) of 2.15 sen, keeping it on track to achieve Kenanga’s full-year gross dividend forecast of 8.7 sen.
Revenue for the quarter rose 18% year-on-year, driven mainly by contributions from six newly acquired properties as well as higher rental rates secured through tenancy renewals.
However, net profit increased at a slower pace of 11%, as higher financing costs from borrowings used to fund the acquisitions partially offset the stronger rental income.
On a quarter-on-quarter basis, both revenue and earnings were broadly stable. Kenanga noted that all property acquisitions announced during FY2026 have now been completed.
The research house highlighted AME REIT’s latest acquisition of an industrial land parcel in i-Park @ Senai Airport City, Johor, announced on July 23.
The REIT acquired the site for RM50.2 million, equivalent to approximately RM130 per sq ft, which Kenanga described as being at the upper end of prevailing market prices due to its location within a mature industrial park with established infrastructure.
AME REIT plans to develop three detached build-to-lease industrial facilities on the site over the next 18 to 24 months.
Kenanga estimates the development could contribute an additional RM2 million in net profit by FY2029.
The REIT’s gearing ratio stood at 0.31 times as at the end of the first quarter, providing room to pursue further expansion opportunities.
Looking ahead, Kenanga expects AME REIT’s earnings growth to be supported by stronger rental reversions as leases are renewed at higher market rates, reflecting robust demand for industrial space in Johor.
The research house also sees continued growth from future acquisitions and development projects, underpinned by Johor’s emergence as Malaysia’s leading manufacturing hub.
It said the Johor-Singapore Special Economic Zone (JS-SEZ), the upcoming Rapid Transit System (RTS) Link, proximity to Singapore and sustained foreign direct investment inflows are expected to drive long-term demand for modern industrial facilities.
With its entire portfolio located within the JS-SEZ, AME REIT is well positioned to benefit from increasing industrial activity, rising rental rates, stronger tenant demand and improved tenant quality as manufacturers continue relocating production amid global supply chain realignments.
Kenanga Research maintained its earnings forecasts and “Outperform” recommendation on AME REIT, with an unchanged target price of RM1.58.
The valuation is based on an FY2027 forecast gross distribution per unit of 8.7 sen, assuming a 2% yield spread over the research house’s unchanged 3.5% 10-year Malaysian Government Securities (MGS) yield assumption.


