


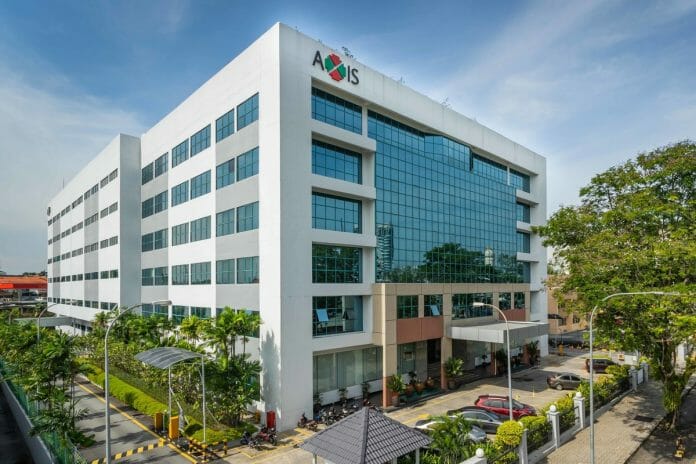
With second quarter results from the REIT sector players released last week, BusinessToday received multiple reports from research houses giving their view on the sector. For this article we chose RHB Research for their in-depth and broad sector overview, that could offer a glimpse on how REIT will perform for the rest of the year.
Notably, RHB Research has maintained its OVERWEIGHT call on the Malaysian real estate investment trust (M-REIT) sector, naming Axis REIT and Pavilion REIT as its top picks despite the sector’s year-to-date underperformance.
The research house said the Bursa Malaysia REIT Index has lagged the broader market, pressured by the expiry of the longstanding withholding tax concession and higher bond yields.
Nevertheless, RHB said second-quarter 2026 results broadly reinforced its positive sector view, with all eight M-REITs under its coverage meeting expectations.
On a market-cap-weighted basis, sector revenue rose 14.5% year-on-year, while earnings increased 15.6%, although both slipped quarter-on-quarter by 3.2% and 6.5%, respectively, largely due to seasonally softer retail performance.
Operating indicators remained healthy, supported by generally stable occupancy rates, positive rental reversions and resilient leasing demand.
RHB also highlighted the sector’s yield spread as supportive. The KLREI-10-year Malaysian Government Securities yield spread stands at about 220 basis points, close to one standard deviation above its long-term mean.
It said while bond yields have risen, weaker M-REIT share prices have also lifted distribution yields, keeping the spread at attractive levels and improving the sector’s risk-reward profile.
Axis Seen Recovering From Temporary Weakness
Among individual names, Axis REIT’s first-half core earnings fell 4.9% year-on-year, compared with growth of 15% a year earlier, due to vacancies at selected properties, rental suspension at Wisma Kemajuan and one-off maintenance costs.
RHB expects these issues to be temporary, with committed leases projected to lift occupancy to 95% by January 2027 from 93% in 2Q26.
The research house also pointed to Axis REIT’s roughly RM456 million acquisition and development pipeline as a key driver of stronger earnings recovery from FY2027.
Retail Margins Could Normalise
For retail REITs, RHB expects net property income margins to normalise from strong first-half levels.
It said the shift in the automatic fuel adjustment from a rebate to a surcharge since May is likely to offset part of the electricity cost savings from the July 2025 tariff revision.
Industrial REITs are expected to be more insulated given their lower utilities exposure.
RHB Economics expects Bank Negara Malaysia’s Overnight Policy Rate to remain at 2.75% into the first half of 2027, while its sensitivity analysis suggests a 25-basis-point rate increase could reduce FY2027 sector earnings by up to about 2%.
Despite these headwinds, RHB expects healthy leasing demand, stable-to-improving occupancy and positive rental reversions to preserve earnings and distribution visibility.
The research house said it favours Axis REIT for its industrial scale and visible acquisition pipeline, while Pavilion REIT remains attractive due to sustained demand for prime retail properties and further rental productivity potential from Pavilion Kuala Lumpur’s ongoing reconfiguration.


