


RAM Ratings has affirmed the AA3/Stable rating of Tanjung Bin Energy Sdn Bhd’s (TBE or the Company) RM4.5 bil Islamic MTN Programme (2021/2041) (the Sukuk).
The agency said the affirmation is premised on the expectation that TBE’s finance service coverage ratio (FSCR) will remain aligned with the rating, supported by standby letters of credit from its sole shareholder, Malakoff Corporation Berhad, and management’s commitment to deploy mitigating measures when required to preserve rating-aligned debt service coverages.
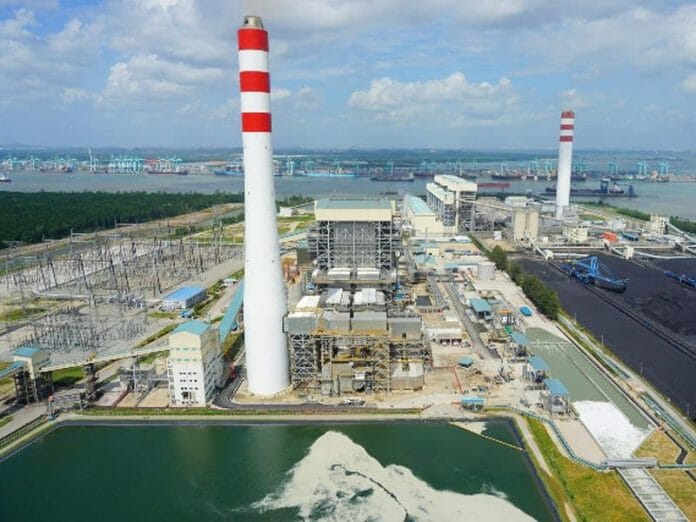
TBE’s 1,000 MW ultra-supercritical coal-fired power plant in Tanjung Bin, Johor (the Plant) resumed operations on 28 January 2026 following repairs to damage caused by an October 2025 fire. Stable operations since recommissioning and the timely receipt of insurance proceeds resulted in cash and bank balances of RM253.32 mil as at end-June 2026. The Company’s FSCR, including cash balances, was 1.65 times on the May 2026 repayment date, exceeding our expectation of 1.50 times.
Going forward, cash retention is expected to come under pressure from higher availability target payments linked to the Plant’s volatile performance over the past five years, increased insurance premiums after the fire incident, and repayments of previously deferred operations and maintenance (O&M) costs to the O&M company.
Based on stressed case projections, RAM indicates that TBE will maintain minimum and average annual FSCRs of 1.50 times and 2.12 times, respectively, over the Sukuk’s remaining tenure. This assumes management retains the flexibility to defer or reschedule selected payments when needed. Cash preservation remains crucial given the transaction’s sensitivity to further material adverse variations.
TBE’s reliance on a single generating unit for its income underscores the importance of its operational reliability. While there is a significant bullet payment due in 2032, refinancing risk is moderated by Malakoff Corporation Berhad’s demonstrated support, the remaining tenure of the Company’s power purchase agreement, and Sukuk’s requirement for liquidity facilities as well as the provision for the sponsor to secure contingent financing ahead of the 2032 repayment date. Like other coal independent power producers, TBE is also subject to regulatory developments, coal price volatility and higher insurance premiums amid the broader transition away from coal-fired generation.


