

The technology sector is entering a more demanding phase of the artificial intelligence investment cycle, where companies will increasingly need to demonstrate actual orders, customer qualifications, capacity utilisation and earnings conversion rather than rely on AI exposure alone, according to Kenanga Research.
Following its attendance at Huatai Securities’ investment forum in Shanghai, Kenanga said AI is moving into what Huatai describes as its “second inning” from 2026, after the 2023-2025 period was largely dominated by large-model training and GPU-led infrastructure spending. The next phase is expected to broaden towards inference, AI agents and commercial applications, driving demand across memory, optical connectivity, power, cooling and advanced packaging.
Kenanga maintained its Neutral stance on the local technology sector, but said it continues to favour companies with visible volume growth, improving utilisation and clear paths towards earnings contribution.
The research house said investors should focus on bottlenecks across five areas of AI infrastructure — compute, storage, optical connectivity, power and equipment — where capacity constraints could create durable opportunities.
Power could become one of the most critical bottlenecks as data centres require not only land and financing but also secure and scalable electricity supply. Huatai believes available power could increasingly determine which projects proceed, how quickly they scale and where major AI hubs emerge.
NationGate Seen Benefiting From Optical Demand
For Malaysia, Kenanga said the emphasis on supply-chain bottlenecks reinforces its positive view on NationGate Holdings Bhd, particularly as global demand for optical transceivers continues to exceed supply.
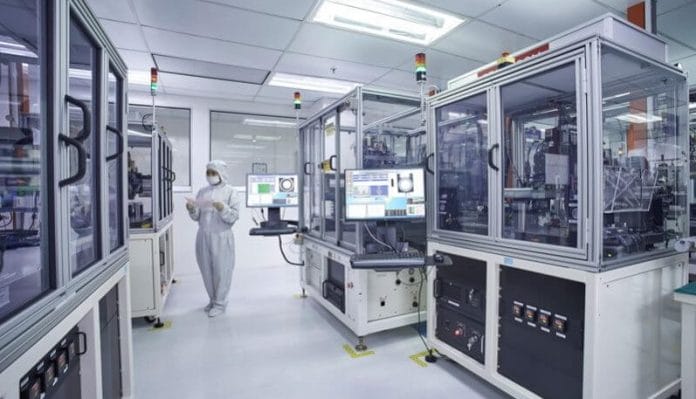
NationGate is expanding beyond conventional surface-mount technology and final assembly into more complex photonics processes, including chip-on-carrier and chip-on-submount packaging, optical assembly, fibre attachment, active alignment, burn-in and optical testing.
Kenanga said NationGate’s targeted production start in November 2026 and subsequent ramp-up will be key milestones, with higher volumes and utilisation potentially providing a more meaningful contribution to FY2027 earnings and margins.
Kenanga has an Outperform call on NationGate with a RM2.14 target price, compared with its Sept 29 closing price of RM1.79.
Other potential beneficiaries include UWC Bhd and AMBEST Group Bhd, which provide equipment fabrication and precision-engineering exposure as semiconductor equipment manufacturers expand output.
Kenanga also highlighted Frontken Corp Bhd, where higher advanced-node semiconductor production could increase demand for precision cleaning and refurbishment services, as well as Kelington Group Bhd, which is positioned to benefit from new fabrication plants and capacity expansion through ultra-high-purity gas delivery systems, process utilities and semiconductor facility engineering.
‘Capacity Expansion Beats Price Increases’
A key message from the Huatai forum was that volume-led growth provides stronger evidence of structural demand than temporary price increases.
Kenanga said investors should increasingly track leading indicators such as new orders, customer qualification, equipment installation, utilisation rates, delivery lead times and power availability rather than wait for the full impact to appear in quarterly earnings.
The report also favoured so-called “toll-road” businesses occupying scarce or difficult-to-replace portions of the AI ecosystem — including advanced manufacturing, HBM memory, optical interconnects, power infrastructure, advanced packaging and semiconductor equipment — because these companies could benefit from industry expansion regardless of which AI model or application ultimately dominates.
Kenanga said Malaysia’s more compelling AI beneficiaries are therefore likely to be the “picks-and-shovels” companies supplying semiconductor equipment, advanced packaging, photonics, data-centre infrastructure and power-related supply chains, particularly where growth is being driven by genuine capacity additions and rising volumes rather than AI-related market sentiment alone.


