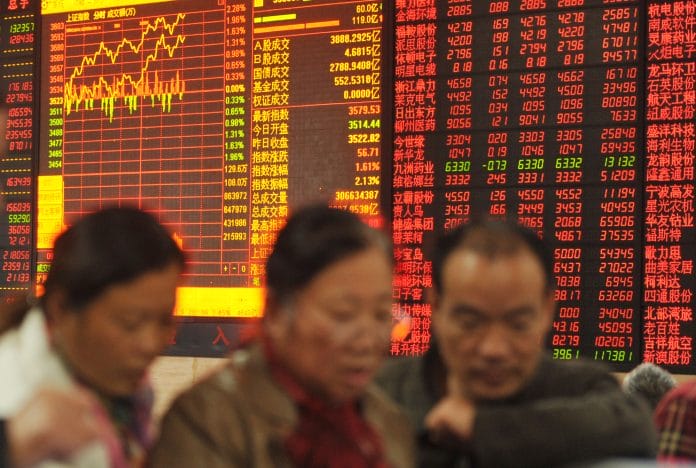
Asian stocks opened October on a cautious footing after a volatile September as elevated bond yields continued to weigh on markets despite softer-than-expected US inflation data reducing expectations of another Federal Reserve rate hike.
MSCI’s broadest index of Asia-Pacific shares outside Japan fell 0.2%, while South Korea’s KOSPI eased 0.14%. Japan’s Nikkei rose more than 1% as chip-related stocks gained, while Nasdaq and S&P 500 futures each added 0.3%.
The stronger performance in Japan came despite weak sentiment elsewhere in Asia, with blockbuster earnings from AI chipmaker Micron failing to provide a broader lift for technology stocks.
“Micron’s numbers are another strong validation of AI and memory demand, but markets may increasingly be asking whether we are closer to peak memory shortage, even if demand continues to exceed supply,” said Charu Chanana, chief investment strategist at Saxo.
“The macro backdrop is also becoming more mixed. Softer US data has taken some pressure off Fed expectations and shorter-term yields, but long-term yields remain high, so the cost-of-capital concern has not really gone away,” Chanana said.
Bond markets remained the main source of concern after a sharp selloff in September. The 10-year US Treasury yield reached 5.306%, its highest since June 2007, while the 30-year yield stood at 5.634% after hitting 5.6517% in the previous session, its highest since June 2002.
Investors are closely watching whether 10-year yields can remain above the psychologically important 5% level.
“In the US, we have surpassed $40 trillion of debt and the fiscal situation shows no sign of improving. So 5% alone, in absolute terms, doesn’t really say much, especially when you think about it in a historical context,” said Darren Shames, global head of rates sales at Nomura.
“But I think it’s the trajectory of the rate move, the velocity that is really getting the attention of investors.”
US inflation rose less than expected in August, prompting traders to reduce bets on a Federal Reserve rate hike on Oct 28. CME’s FedWatch tool showed a 38% probability of a hike, down from 50% a day earlier.
The dollar remained near a two-month high as elevated Treasury yields supported the US currency. The euro was at US$1.1334 after falling 2.5% in September, while the yen weakened 0.3% to 157.95 per US dollar.
The Bank of Japan is also facing pressure over the pace of its monetary tightening, with a summary of opinions from its September meeting showing some policymakers saw a need to accelerate rate hikes.
Oil prices were broadly steady, with Brent crude at US$98.15 a barrel after rising more than 14% in September, its third consecutive monthly gain.
Markets are also monitoring stalled US-Iran peace talks, with the conflict keeping energy prices elevated and adding to concerns over inflation.
Reuters