
Newly listed SLGC Bhd is positioning itself for a stronger push into higher-margin industrial construction after its ACE Market debut, while targeting the recognition of about RM800 million from its RM1 billion unbilled order book across its financial year ended 2026 (FY26) and FY27.
In an exclusive email interview with BusinessToday, SLGC Bhd Managing Director Yong Zhen Lin said the secured order book provides the construction group with strong earnings visibility, while its tender pipeline is increasingly weighted towards commercial and industrial (C&I) projects, particularly industrial buildings.
Yong said SLGC’s tender book is typically much larger than its outstanding order book at any given time, although the group does not disclose a specific pipeline value. Its historical tender success rate has been around 10% to 15%.
Industrial Jobs Take Centre Stage
While SLGC’s existing RM1 billion order book is predominantly residential, Yong said the opportunities ahead are increasingly coming from the C&I segment.
Industrial projects can offer better margin potential as they typically involve greater technical complexity and customisation, he said.
SLGC has built experience through projects including Daiwa Warehouse Phase 3 and the Secret Recipe Factory, while developing capabilities in multi-storey warehouses and other specialised facilities.
Yong said the shift does not mean SLGC is moving away from residential construction, with the group continuing to evaluate opportunities across all its existing segments.
Potential projects are assessed based on the customer’s reputation and financial standing, project viability, expected returns, resource requirements and the impact on existing commitments.
“Our objective is to secure projects that make commercial sense rather than simply growing the order book for the sake of size,” he said.
IPO Proceeds Boost Project Capacity
Following the listing, Yong shared that SLGC is deploying part of its IPO proceeds to strengthen its operating capacity and balance sheet as it pursues larger projects.
“On that note, the group has allocated RM9.2 million for construction machinery and equipment, including aluminium formwork and passenger hoists,” Yong said, while highlighting that greater equipment ownership would reduce reliance on rentals, improve project scheduling and cost management, minimise potential downtime and give SLGC greater control over project execution.
He also highlighted that the investment could improve the group’s competitiveness when pricing for new tenders, with the allocation expected to be utilised within 24 months.
On the other hand, Yong shared that another RM7.5 million has been earmarked for working capital to support construction expenditure that typically occurs ahead of progress billings and collections.
Yong said the additional funding becomes increasingly important as SLGC takes on larger or longer-duration projects, which can run for between two and five years.
Gearing Set To Improve Post-Listing
Meanwhile, SLGC is also allocating RM7.6 million to repay bank borrowings, which is expected to strengthen its financial position.
Yong said the group’s gearing ratio is expected to improve from 3.43 times to approximately 1.67 times following the listing and utilisation of the IPO proceeds, while net gearing is projected at around 0.5 times.
Lower borrowings should also reduce SLGC’s exposure to finance costs, particularly on facilities carrying floating interest rates, while giving it greater flexibility to evaluate larger projects without overstretching its balance sheet.
Earnings Delivery Now In Focus
SLGC opened at 28 sen on its ACE Market debut, matching its IPO price. A total of 308,622 shares changed hands during the opening session, according to Bursa Malaysia data.
At its IPO price, SLGC carries an estimated market capitalisation of RM156.8 million.
Yong said investors should look beyond the headline valuation and focus on the group’s earnings delivery, order book size and future contract wins.
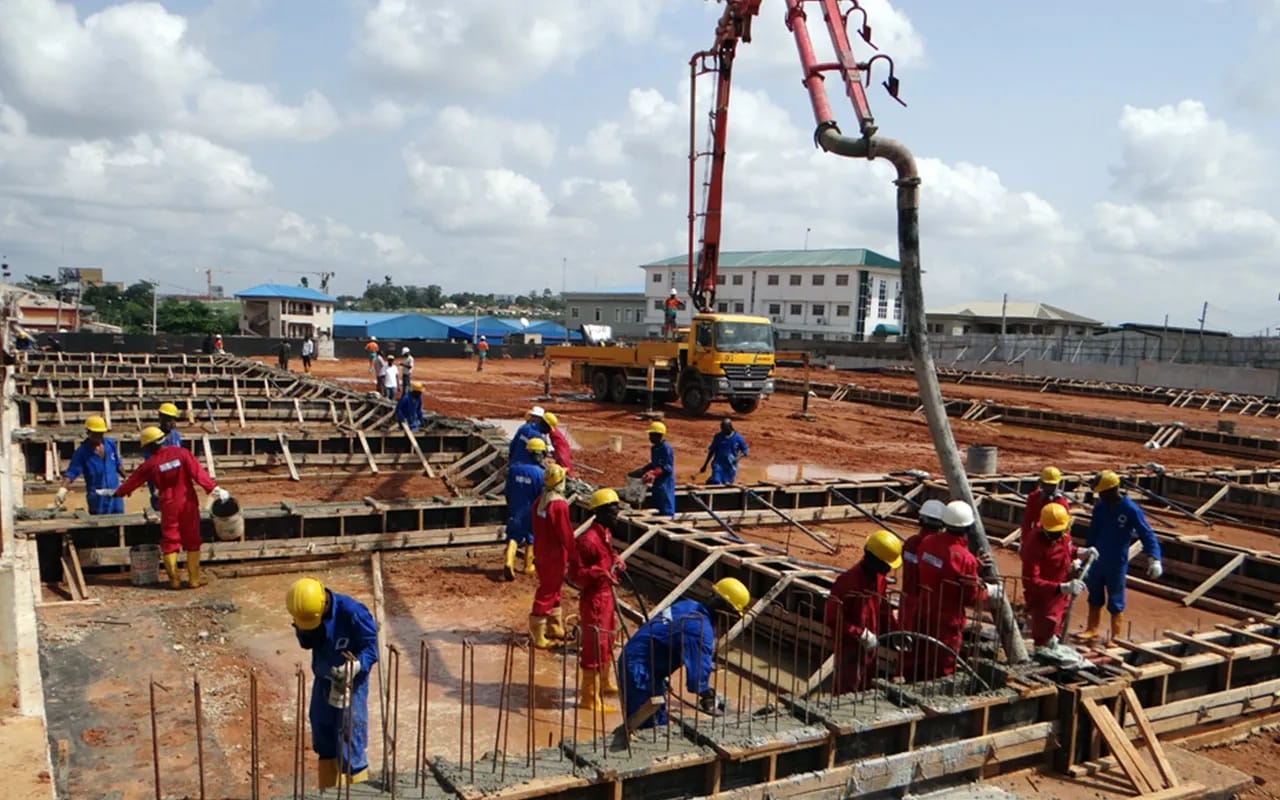
He pointed to SLGC’s approximately RM1 billion unbilled order book, track record across C&I and residential construction, and capabilities in design-and-build, value engineering and Industrialised Building System methods as key fundamentals supporting its longer-term prospects.
Following the listing, SLGC’s promoters and substantial shareholders collectively retain 70% of the group, while the public float stands at 30%.
Yong said the offer for sale, representing 11.3% of enlarged share capital, should be viewed as part of broadening SLGC’s public shareholding rather than an exit by existing shareholders.
For investors, Yong said the key milestones after listing will be the execution of SLGC’s existing order book and future contract wins, both in terms of value and project type, as the group works towards becoming a larger construction player while maintaining disciplined cost management and a healthy financial position.