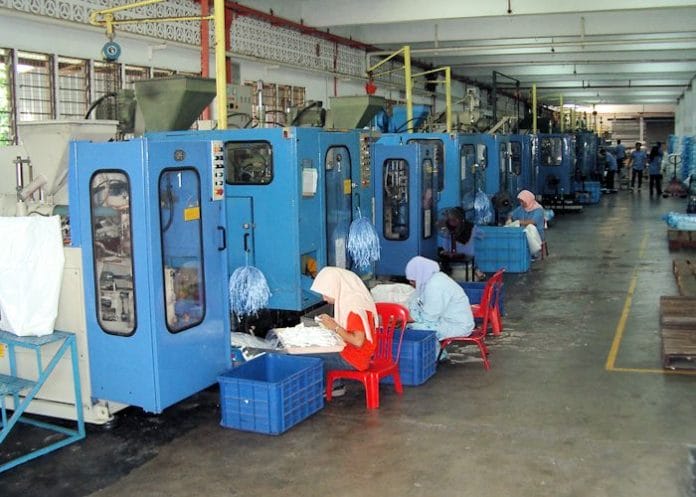
Kenanga Research has maintained a Neutral outlook on Malaysia’s plastic packaging sector, citing continued headwinds from global trade uncertainties, intense competition, currency fluctuations and weak resin prices, which are expected to weigh on earnings visibility into CY26.
In its latest sector review, Kenanga said while demand for premium, consumer-used packaging products remains encouraging, overall profitability continues to face pressure as average selling prices (ASP) decline amid falling resin prices and a strengthening ringgit.
“Despite broadly stable aggregate revenues, sector profitability has weakened, reflecting margin compression,” the research house noted, pointing to softer profit-before-tax trends across the industry.
Global Trade Risks and Tariff Spillovers
Kenanga highlighted that direct exposure to higher U.S. tariffs is relatively limited, as exports to the U.S. account for less than 10% of sector revenue. However, heightened trade tensions have introduced broader uncertainties, particularly as plastic packaging films are widely used in business-to-business (B2B) and inter-country trade.
“A slowdown in global trade volumes would likely dampen demand for plastic packaging materials,” Kenanga said.
Among sector players, Scientex stood out as the only company with a manufacturing plant in Arizona, U.S., which has recorded improving orders and potentially better ASPs in 2Q–3QFY25 as it serves U.S. customers more directly.
Competition Intensifies Amid Overcapacity
The sector has also faced heightened competition since CY24, driven by industry overcapacity. Kenanga noted that many manufacturers continue operating older production facilities alongside newer thin-gauge lines, allowing for aggressive marginal pricing of legacy products.
Competitive pressures have been further exacerbated by Chinese producers diverting excess supply to Southeast Asia, following softer demand from U.S. and European buyers. Kenanga’s visit to the Shanghai World of Packaging (SWOP) 2025 exhibition suggested that pricing competition is likely to persist and potentially intensify.
Stronger Ringgit Pressures Margins
Currency movements have added another layer of pressure. In 9MCY25, the average USD/MYR exchange rate strengthened to RM4.33, compared with RM4.63 in 9MCY24, creating near-term foreign exchange headwinds for export-oriented players.
Kenanga expects the ringgit to strengthen further to RM3.95/USD in 2026, from around RM4.05 currently. The research house estimates that every 1% change in forex rates could impact sector profitability by 2%–3%, largely due to timing differences in inventory purchases, sales confirmation and receivables collection.
Resin Prices Remain a Drag
Resin prices declined 10%–15% year-on-year in 2HCY25, contributing to lower ASPs across the sector. Based on industry feedback, Kenanga expects resin prices to remain soft over the next 12 months, in line with the U.S. Energy Information Administration’s bearish outlook on global crude oil prices for CY26.
Given the lack of near-term earnings recovery catalysts, Kenanga does not foresee a sector re-rating in the near future.
Earnings Revisions and Target Price Adjustments
To reflect softer resin prices, Kenanga trimmed its FY26 earnings forecasts for: Thong Guan Industries (TGUAN) by 4%, and Scientex Packaging (SLP) by 8%.
Target prices were also revised:
- TGUAN: TP cut by 11% to RM1.29, following a roll-forward of its valuation base to FY26.
- SLP: TP reduced by 9% to RM0.81, alongside a lower FY26 dividend forecast of 4.1 sen, resulting in a Market Perform call.
Earnings forecasts for Scientex were left unchanged, as upside from its U.S. manufacturing operations is expected to offset sector-wide margin pressures.
Selective Positives Remain
Despite the challenging outlook, Kenanga highlighted cost-saving initiatives across the sector. The completion of solar panel installations by players such as Scientex and BP Plastics (BPPLAS) is expected to deliver energy cost savings of about 10%, with full benefits materialising in CY26.
Kenanga remains positive on TGUAN (Outperform; TP: RM1.29), citing:
- Strong growth momentum in the food and beverage packaging segment,
- Expansion into overseas markets with environmentally friendly, high-performance products, and
- Upcoming income recognition from its property development segment starting in CY26.
At current levels, TGUAN is trading at a nearly 25% discount to its 10-year historical forward P/E average of around 9 times.
Meanwhile, Kenanga downgraded SLP to Market Perform, noting that the stock is trading at a trailing P/E of about 19 times, in line with its long-term historical average.